The near-Dickensian language of a Will doesn’t half make the clarity of its contents harder to grasp, doesn’t it?
And then there’s LPAs, which come with limits that catch you out. Things like what an attorney can and can’t gift, whether they can set up a trust, what happens if the attorney themselves loses capacity.
So if you’re prone to befuddlement – and, let’s be honest, who isn’t? – then tune into this conversation with Shaun Moore, Technical Specialist at Quilter.
Because Shaun joined us for a lunch-hour conversation that’s all about deciphering what wills and LPAs actually say.
But this isn’t about which form to fill in or which portal to log into. It’s a planning conversation about why these documents matter, what they can and can’t do, and what paraplanners need to look out for.
And with pensions becoming vulnerable to IHT, and plenty of plans now out of date, this is the ideal time to revisit both documents.
So during this Assembly we covered
- why pensions coming into the estate means old wills need a second look
- Residence Nil Rate Band (RNRB) pitfalls and old discretionary trusts left over from before the transferable nil rate band
- deeds of variation, and what your options are when a will hasn’t been drafted well
- investment powers in will trusts, including bonds for life tenants, STEP provisions and when the Trustee Act 2000 defaults apply
- the limits on what an attorney can do, including gifting and setting up trusts
- LPAs and discretionary fund management, and the Office of the Public Guardian’s reversed guidance on discretionary fund management (now allowed unless the document says otherwise)
- what happens when an attorney themselves loses capacity, and whether a will can be changed or revoked
What can you expect to take away?
Watch or listen and you’ll gain a clearer idea of the role of wills and LPAs so you can spot the planning opportunities.
Would you trust a fun fact you can’t find in black and white?
That’s just one of the questions rattling around in this episode – the first-ever podcast-only instalment of the Self-Assembly Paraplanning Show. It’s a regular, unscripted conversation where a small group of paraplanners compare notes on what’s actually happening in their world.
This episode’s host Sam Tonks, is joined by Julie South, who runs outsourced paraplanning business, Bee Paraplanning, and Steven McBurnie, a Senior Associate at RBC Brewin Dolphin and is currently on the pathway to becoming client-facing.
Across the hour they cover:
- when is a ‘fun fact’ actually ‘fact’? How do you know and why does it matter?
- CPD opportunities hiding in plain sight – why “research before a case” counts as CPD
- AI in paraplanning – where it genuinely helps (source-checking, drafting) and why it hasn’t replaced the trust between adviser and paraplanner
- GP records, data silos, and why medical underwriting keeps stalling protection cases, and the wider frustration of providers who won’t pick up the phone
- smart glasses, meeting recording, and where data collection starts to feel like too much
- clients turning up to meetings having already run their suitability report through ChatGPT or Copilot
The episode wraps up with events for your diary and some very unfinancial recommendations for the Summer holidays.
Even very experienced paraplanners can trip over obstacles lurking in the shadows of IHT.
So we invited Aegon’s tax and trusts manager, Elaine Cruickshank, to join host, Richard Allum, for an online Assembly to help you dodge the IHT perils.
Over the course of one lunch-hour, Elaine:
- untangles the transferable nil rate band and residence nil rate band, including the detail that trips people up around second marriages and downsizing provisions
- gets into the finer points of gifting exemptions, PETs and CLTs, beyond the seven-year headline
- explains how the inclusion of pensions in estates affects the taper threshold, and what that means for clients close to the £2 million mark
- works through charitable giving and the 36% rate, including the added complications once pension funds are in the mix
- brings it all together with planning opportunities you can take straight back to your desk
What can you expect to take away?
Watch or listen now and you’ll have a sharper grasp of the IHT detail that’s easy to get wrong. Plus the confidence to spot these issues in your own client cases.
Watch or listen now
Missed it? Then follow the links below to download Elaine’s slides, watch the replay or catch up with the podcast now.
The outstanding questions
There were so many questions on this Assembly that we ran out of time, so Elaine has provided us with the answers to the outstanding questions, as well as provide a clarification on the final question of the Assembly.
Can the small gifts exemption and the annual £3,000 exemption be given to the same recipient?
If a gift in excess of the £250 small gifts exemption is made, then as this gift is more than the small gifts exemption, the full gift would be allocated against the annual exemption (assuming that this was available).
Why is it called Inheritance Tax? Shouldn’t it be called Estate Tax, as it is (normally) the estate that pays?
“Inheritance Tax” is a better reflection of what the tax is intended to cover — rather than simply being a tax on an estate at death, there could also be IHT applying to lifetime transfers.
Is it best to space significant gifts at least 7 years apart then?
Each gift has its own 7-year clock, but whenever a gift is being made you have to consider the cumulative impact of any gifts made in the previous 7 years. If the donor dies within 7 years of a gift, earlier gifts use up the nil-rate band first before later gifts are considered. Making very large gifts close together can therefore increase the IHT exposure of later gifts, if death occurs within 7 years. Taper relief may reduce the IHT on gifts made more than 3 years before death, but it does not reduce the value of the gift itself for nil-rate band purposes.
Does tax-free income from a beneficiary’s pension (where the spouse dies under age 75), either through an annuity or under FAD, count towards regular income when considering gifting out of surplus income?
This is a grey area and will probably require a tax case to provide clarification. As this money is completely exempt from income tax, HMRC could view the regular withdrawals of this nature as capital rather than income.
Is there a length of time for the ‘main residence’ qualification to be lost?
For the Residence Nil Rate Band, there is no specific minimum or maximum period between the property ceasing to be the deceased’s main residence and their death. The key point is that the property must have been a qualifying residential interest, meaning a property that the deceased occupied as a residence at some point during their ownership. For the downsizing addition, they have to downsize or dispose of the property on or after 8 July 2015, but there is no stipulated timeframe between the date of downsizing/disposal and death.
What if they still own the property but have also moved into a care home?
A property can qualify even if the individual was living in a care home at death, provided the property had been their main residence at some point and they leave the property to their direct descendants. The amount of residence nil rate band available will generally be the lower of the available RNRB and the value of the qualifying residential interest passing to direct descendants, and it may also be reduced by the taper reduction if the estate exceeds £2 million.
If they own a house worth less than the RNRB, should they upsize to make the most of it?
If they upsize and buy a bigger house, the value of the estate would generally remain unchanged — they now have a larger property and less cash. However, if they live in the bigger property as their main residence and leave this to their direct descendants in their will, then they could in theory qualify for the full residence nil rate band if the value of the house was equal to or higher than the residence nil rate band and the £2,000,000 tapering threshold was not breached. However, tax mitigation isn’t the only factor to consider here — there would be the costs of moving house, larger council tax and utility bills etc, which could be more significant than any IHT saving achieved.
Can RNRB apply to an IIP trust, where some people have moved their home into a solicitor’s trust and continued to live in it?
It sounds as though this type of arrangement would potentially be a gift with reservation of benefit, with the value of the property remaining in their IHT estates. Whether or not the RNRB would apply in this scenario would depend on the provisions of the trust. Are the direct descendants the beneficiaries of the trust, and do the trust provisions meet the conditions of ‘directly inheriting’ the property?
You’d be forgiven for thinking that a gathering of previous award winners could turn into a smugfest.
But it’s PARAPLANNERS that we’re talking about.
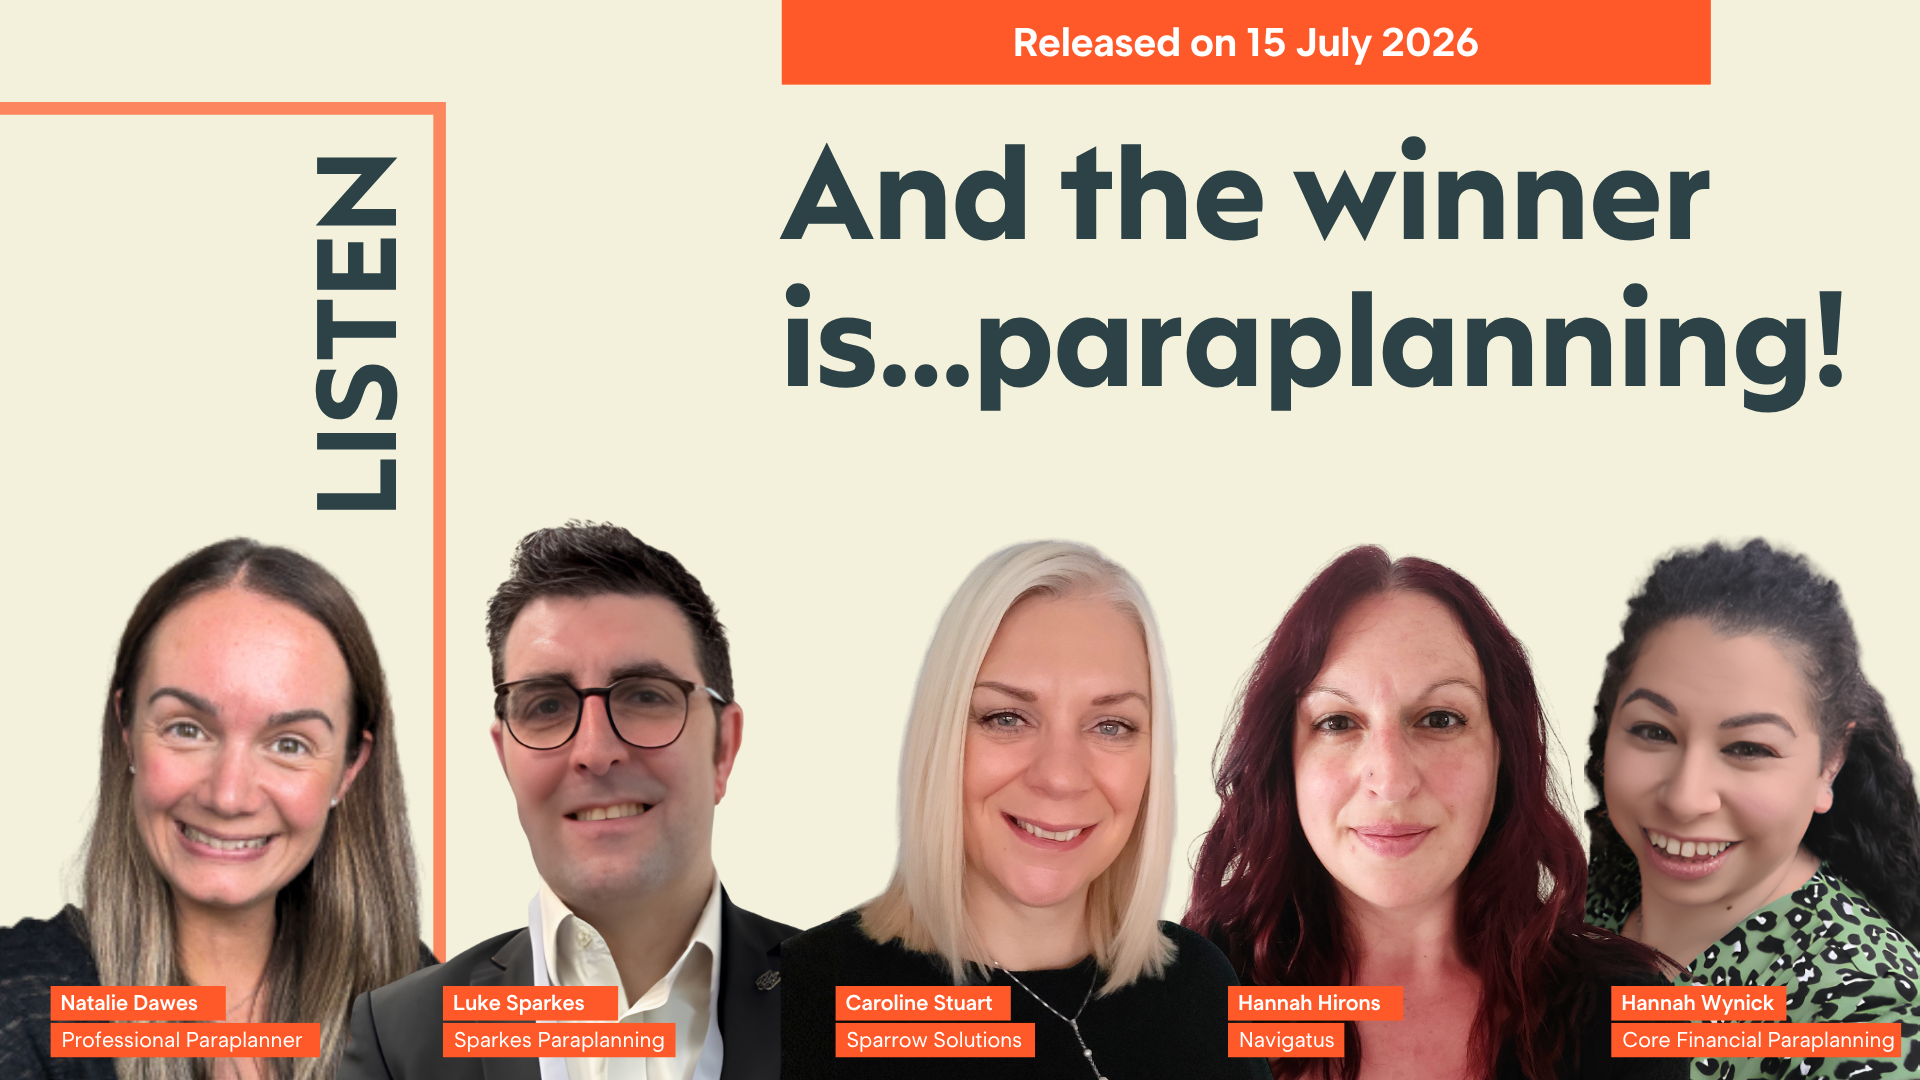
So this episode – recorded specially to celebrate the tenth annual Professional Paraplanner Awards – is far from self-congratulatory. In fact, it’s packed with thinking that will inspire every paraplanner wherever you are in your career.
Why? Because it illustrates how entering an award – or even just thinking about it – is one of the most helpful ways to reflect on your career, what you’ve achieved and what you would like to achieve in the future.
Host Caroline Stuart of Sparrow Solutions is joined by Natalie Dawes, editor of Professional Paraplanner, along with three paraplanners who’ve been through the process themselves: Hannah Hirons of Navigatus, Luke Sparkes of Sparkes Paraplanning, and Hannah Wynick of Core Financial Paraplanning.
In an hour-long chat they talk about
- overcoming your imposter syndrome
- why nominating yourself is OK even when it might not feel like it
- why being nominated by someone else feels ACE
- whether there’s a difference entering awards when you’re in-house versus outsourced
- why writing an award entry helps you realise what you’re actually good at
- what it’s like to sit in an interview with judges – and why it’s so valuable
What’s more, the conversation also recognises that some people just don’t want to enter awards or feel the need to do so and explores ways in which paraplanners can receive the recognition their work deserves.
Above all, this is an episode that illustrates how powerful it can be for paraplanning practitioners to reflect on their professional progress. And how the peer-led evaluation of entries has quickly established the Professional Paraplanner Awards as the preeminent standard for the paraplanning profession.
An odd feature of paraplanning is that quite a bit of our time is spent designing strategies that are all about the inevitability of death but – just like in our everyday lives – lots of our clients seem reluctant to talk about death and dying and being prepared for it.
Yet the financial grief that families and friends face following a death serves only to compound the overwhelming emotional kind.
That’s what this Assembly is all about. Kylie Clark of Wealthtime, Katy Hancock of Dorothy House Hospice Care and Lucy Halliday from Argonaut Paraplanning joined Richard Allum to talk about death and dying.
Because at a time when a growing percentage of clients are reaching an age when they should be dotting the i’s and crossing the t’s in plenty of time before they die, what can paraplanners do to help them get death-ready?
What you’ll learn
- Out-of-date expression of wish forms, account and app passwords, overseas accounts, tracking down former advisers and solicitors – what are the biggest and most frequent problems following death? And what can clients and their families do to avoid them?
- The way firms handle bereavement is one of the most significant sources of complaints across financial services. With bereavement support about to come under the FCA’s spotlight, what can advice practices do to improve things?
- Learn how the ‘last 1,000 days’ concept could offer a lens to help clients and their families plan
- Grief isn’t just the client’s, it’s the paraplanner’s too. How we’ve been able to acknowledge grief in the past influences how we’re able to help clients experiencing it now and in the future.
Watch or listen now
Paraplanners from all across the UK got together to share ideas, ask questions and break the big taboo about death. Plus there’s one hour’s CPD available.
Missed it? Then follow the links below and watch the replay or catch up with the podcast now.
Salary sacrifice – or salary exchange – has been around for ages. But a proposal in last autumn’s Budget to cap the national insurance relief available on pension contributions has brought it into sharp focus.
We racked our brains but don’t think that we’ve ever explored the essentials of salary sacrifice for paraplanners so, while the Finance Bill is making its way through Parliament, we decided to invite Lucy Clark and James Jones-Tinsley from Barnett Waddingham to tell us what it’s all about and what’s changing in future.
Lucy explains:
- what salary exchange actually is
- the national insurance savings it can unlock – for employees and employers
- the different ways to structure it
- the things that can go wrong
James rounds off the 30-minute briefing by explaining the latest on the progress of the proposed cap, which is due to come into effect by 6 April 2029, and why its final form is far from settled – and may not even happen.
The tax landscape has shifted significantly over the past couple of years. Allowance reductions, rising dividend tax rates and the proposed extension of IHT to unused pensions means there’s plenty for paraplanners to get to grips with — and plenty of opportunity to add real value for clients.
This Assembly cuts through the complexity and gives you a clearer picture of how different tax wrappers work in practice, so you can make more confident decisions about which solution is right for which client.
Host, Richard Allum is joined by Elaine Cruickshank, tax and trusts manager at Aegon for a practical, no-nonsense look at onshore bonds, offshore bonds, GIAs and trust solutions with an agnostic perspective that keeps the focus firmly on what’s best for the client in front of you.
What we explored
We looked at how recent tax changes are prompting advisers and paraplanners to revisit wrapper choice, and went through the kind of comparative thinking that helps you work out when a bond might be preferable to a GIA or when onshore makes more sense than offshore.
We also looked at how onshore bonds are actually taxed (including a common misconception that’s worth clearing up), which wrapper tends to suit which client circumstances, and how trust solutions fit into the picture, particularly in the context of the proposed IHT changes to pensions.
What can you expect to take away?
After catching up on the Assembly, you’ll have a clearer understanding of the tax treatment of different wrappers, a more confident sense of when each option is likely to work best, and some practical frameworks for thinking about trust planning solutions.
We’ve been recording ‘Technically speaking’ sessions with Utmost’s Steve Sayer for a few years now.
And because they offer really crunchy case-study based content, they’re really popular with paraplanners.
But we like to plan ahead so late last year, we sat down with Steve and the team at Utmost to talk about the ‘Technically speaking’ plans for 2026. During the conversation, Steve talked about each of the major tax planning milestones that stem from the measures announced by the Chancellor since October 2024 and stretch ahead to 2031.
And when Steve revealed that he had a single slide that set out each of the changes against a timeline, we decided – there and then – that was definitely something paraplanners would like to hear more about.
So we invited Steve into the studio to talk us through it.
And here’s the result: Steve Sayer’s guide to the tax change timeline until April 2031. In it, Steve covers inheritance tax and the domicile regime, excluded property trusts and the new foreign income and gains regime, the agricultural and business property relief changes, pension death benefits in 2027, plus the effects of the freezing of tax bands until 2031.
Plus you can download his slide using the link below.
The Government’s Finance Bill which includes the provision for pensions to become subject to inheritance tax (IHT) has reached a critical point in its progress through Parliament.
But as James Jones-Tinsley of Barnett Waddingham explains in this 15-minute briefing recorded especially for the Paraplanners’ Assembly, the measure isn’t necessarily a done deal.
Why the next few weeks matter
He suggests that the government’s recent decision to raise its proposed threshold on agricultural and business property relief from £1 million to £2.5 million indicates that the government can be persuaded to rethink its plans.
So the next few weeks matter. And that’s why James is encouraging advice professionals and clients to write to their MPs – not least to encourage the government to consider the practical consequences of its planned changes.
For instance, how reasonable and realistic is it to expect personal representatives, many who are likely to be recently bereaved family members, to successfully negotiate their way through complex pension death benefit rules against the clock?
And is adding to the anxiety of family members worth it when the government’s own projections suggest this will raise £1.5 billion by 2029-30 – a fraction of the £6 billion that is already being collected thanks to freezing of allowances?
What you’ll learn by watching and listening
If you want to know the latest on the progress of the law resulting from last November’s budget and its consequence for advice colleagues and clients, then you’re in the right place.It’s more than a year since speculation ahead of last autumn’s Budget led to a surge of savers raiding their pension pots in a bid to beat rumoured changes to tax-free lump sums.
But when no changes were announced and people sought to reverse their withdrawals, they discovered that the 30-day cancellation rule didn’t apply. Or did it?
That confusion over conduct of business rules led to calls for HMRC and the FCA to clarify whether or not savers could cancel – and they’ve now responded.

In the second of her two-part special on AI in paraplanning, Zara Okoro asks where we are heading as a profession. What plans are AI tool providers and financial planning practices likely to pursue in future? And what could it mean for the role of paraplanner itself?
In conversation with Benjamin Fabi of Principled Paraplanning, Aram Kupelian of Holden and Partners, Jonny Stubbs of Brooks Financial, and Ben Wright of Melo, Zara asks how far and fast AI adoption should go, what could go wrong, and what needs to happen to get this right?
Our last episode looked at where AI in paraplanning stands today.
For this concluding episode, we’re looking ahead.
Useful links and downloads
As well as links to the podcast episode on Spotify, Apple and Acast, we’ve included downloads of Harriet Mayer’s slides on AI and paraplanning from The Big Day Out in 2025, and Harriet’s glossary of AI terms too.