A Kerr-Fuffell family member has snuffed it. But was it foul play? Join paraplanner sleuths to sift for clues and crack the case.
You’re invited to a Big Day Out with a difference.
Because we’d love you to gather with paraplanners from across the UK at West Horsley Place in Surrey from 9am on Tuesday 3 November 2026.
Over the course of the day, you’ll work out which member of the Kerr-Fuffell family stood to gain most from the untimely demise of their (perhaps not so) loved one.
Our writers room of supremely well-qualified paraplanners is busily concocting a series of – fingers crossed – interconnected case studies.
Inheritance tax, pensions, estate planning, wills, lasting powers of attorney, divorce, protection – you name it – we’ll cram it in.
In other words, you’re guaranteed an agenda that will be bursting at the seams with seven hours’ worth of CPD. That’s knowledge and insights that you can apply to client cases right away.
How will the day work?
At 10am, we’ll gather in the Great Hall for your briefing on the untimely demise of Lady Fifi.
Then you’ll join one of four groups, each led by a duo of paraplanning detectives.
In a series of sessions, your group will meet with expert witnesses drawn from our supporters – that’s Aegon, Howden, M&G, Quilter, Scottish Widows, Transact and Wealthtime – to sift evidence contained in case studies.
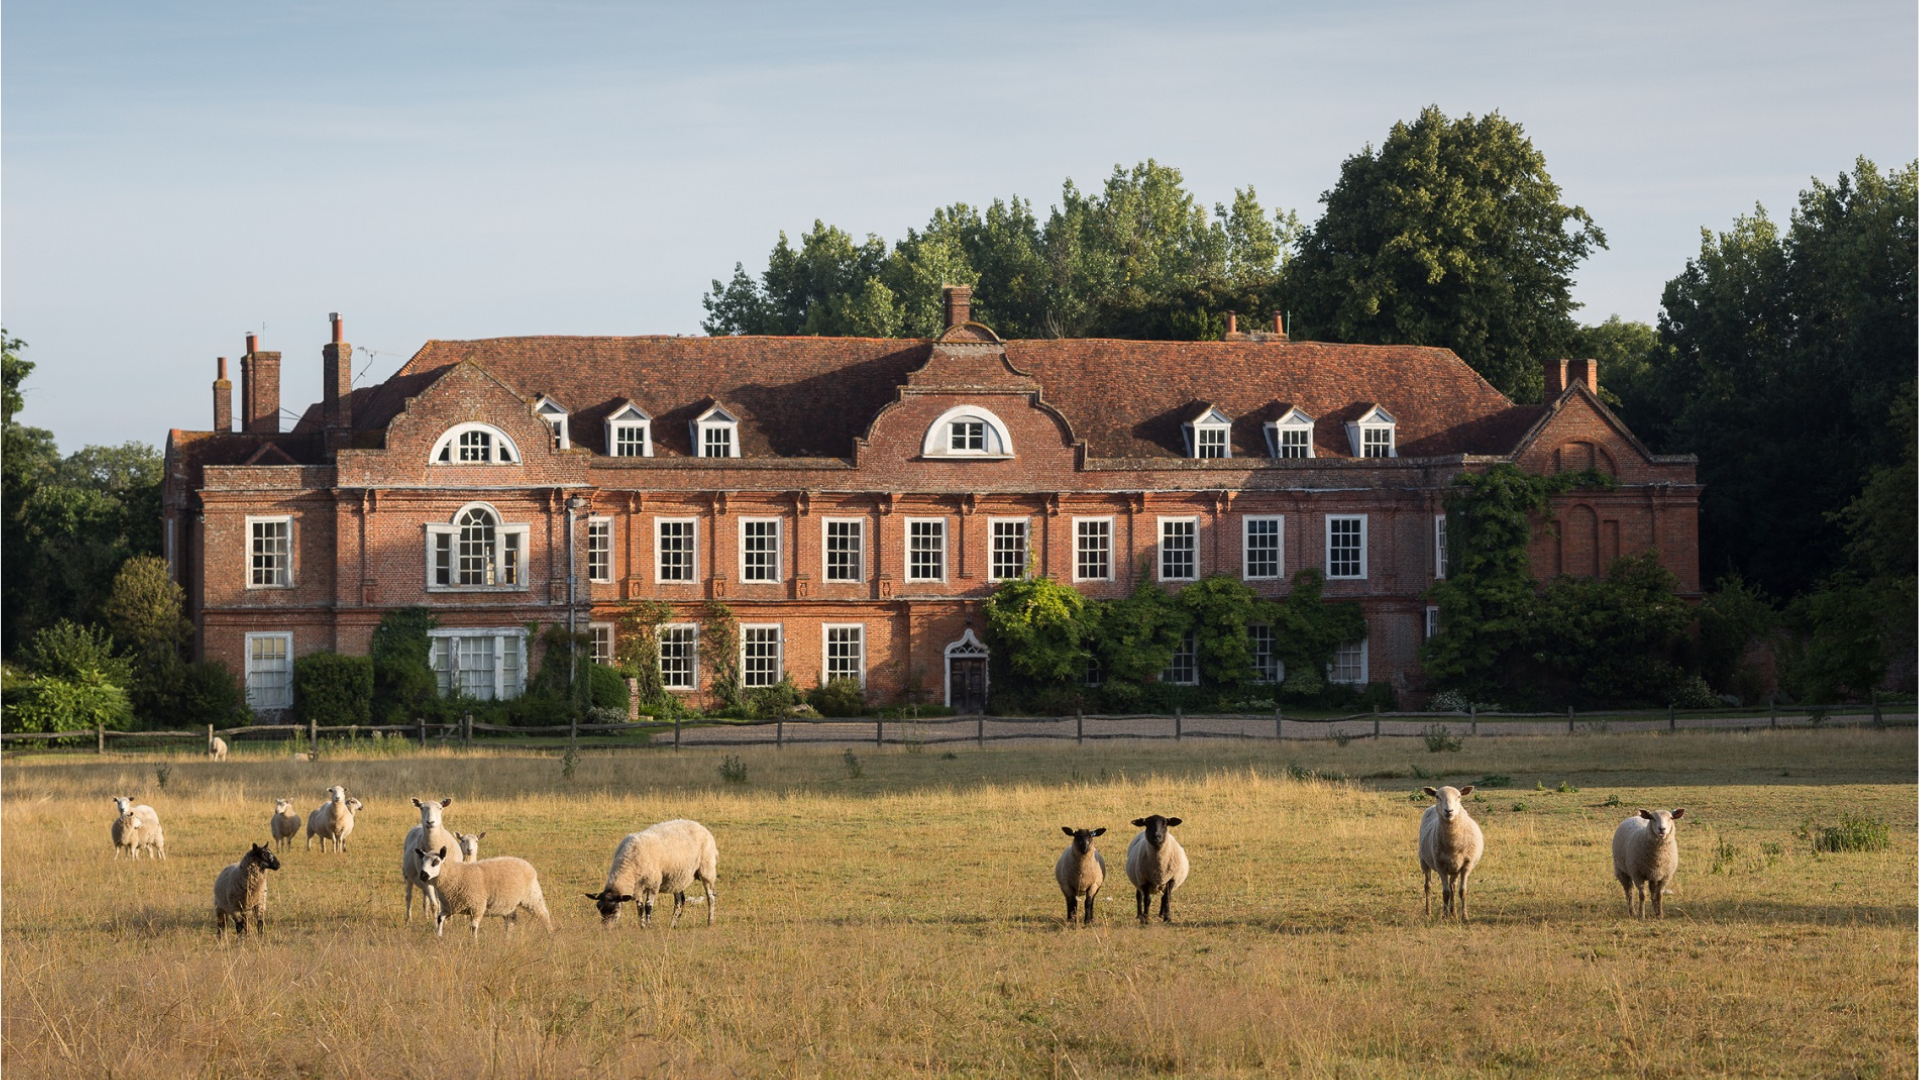
Whoa there! Why does West Horsley Place look familiar?
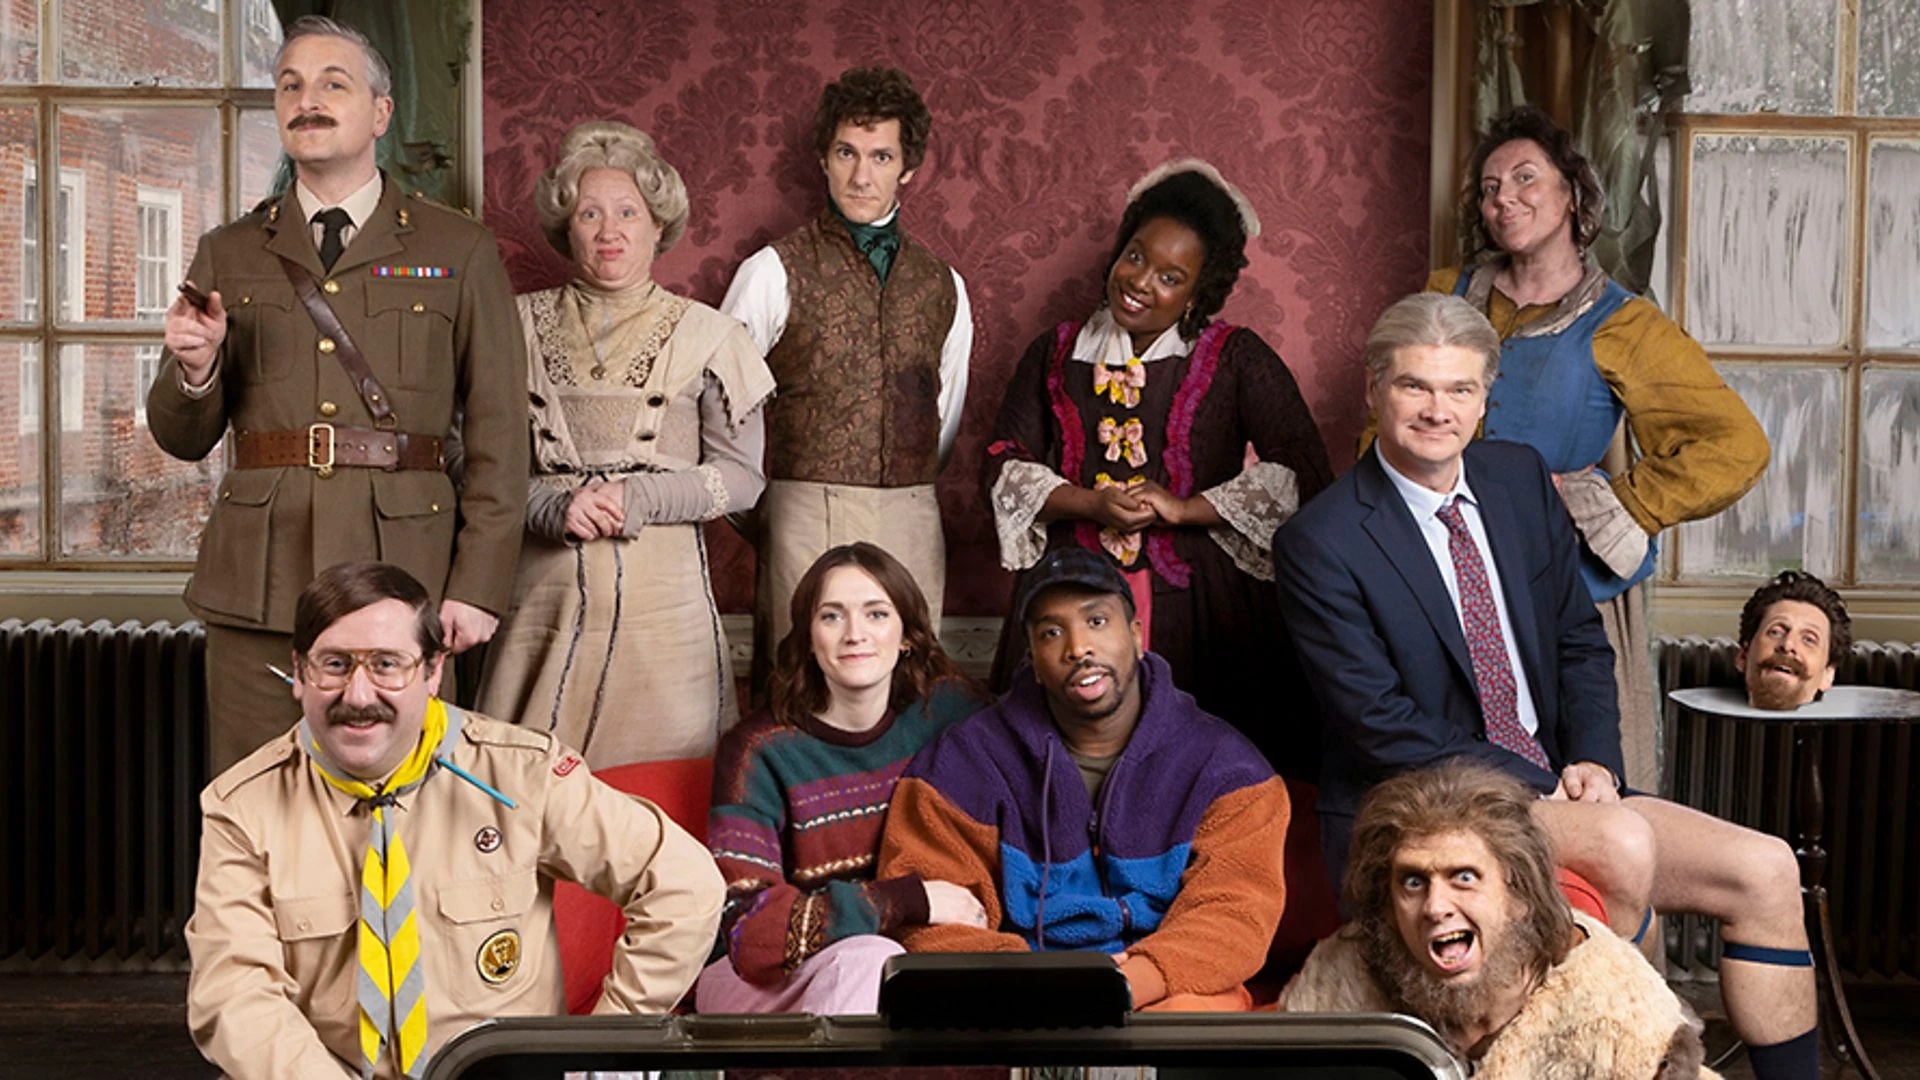
If you’re a fan of the hit BBC TV comedy ‘Ghosts’, it will.
Because West Horsley Place is Button House!
And do you know what? It looks EXACTLY like it does on the telly – outside and in.
So not only will you get to take part in the Big Day Out, you can sneak a few selfies in the Great Hall, the library, that long red room upstairs, the grand staircase, the garden, even the corridor that leads to the plague pit.
What’s more, we’ll take the traditional ‘school photo’ in front of house.
How exciting is that?!
And in a happy coincidence, we’ll be gathering for our Big Day Out just one week after ‘Ghosts: The Possession of Button House’ is released in UK cinemas.
Will you feed me?
This is a Paraplanners’ Assembly event, so we won’t scrimp on the catering.
Your ticket includes breakfast baps (or butties) on arrival, a delicious hot buffet lunch, plus a sweet treat with your tea in the afternoon.
There will be vegetarian and vegan options. And if there are ingredients you need to be careful of, let us know when you book, and we’ll take care of that.
Surrey? But that’s far far away!
It’s a fair cop. For 12 years we’ve hosted events in the Midlands-ish, so it was reasonably easy for people to get to.
But getting exclusive use of a country estate for a whole day’s Whodunnit that’s just the right size for a Big Day Out – well, that’s quite tricky.
Being big ‘Ghosts’ fans, when we discovered we could have Button House to ourselves for the day, we couldn’t resist.
We know Surrey is a stretch. And if that means you don’t feel able to join us this year, we’ll make it up to you next year. Promise.
Getting there
By car: West Horsley Place is off the A246 between Guildford and Leatherhead. It’s ten minutes’ drive from the A3/M25 intersection. Leave the A3 at junction 10. You can park for free in the visitor car park.
By train: Horsley station is one mile away, with frequent trains from London Waterloo (49-minute journey), Vauxhall, Clapham Junction and Guildford (14-minute journey). Woking station is 8 miles away, with frequent, fast trains to and from London. It takes about 25 minutes to walk from the station to West Horsley Place. It is a lovely walk through the estate, but you will need footwear suitable for wet, muddy or uneven ground. Follow the bridleway and you’ll arrive in the car park and welcome area.
By bus: The 479 Guildford-Bookham-Leatherhead-Epsom service operates roughly hourly. The nearest stop is East Horsley, Duke of Wellington. It takes approximately 7 minutes to walk from the stop. The entrance to West Horsley Place is on the right before you reach St Mary’s Church. Walk down the drive to reach the Welcome Area next to the Barn.
Here’s the bus timetable: Service 479
Where to stay
West Horsley Place has plenty of places to stay. There are two large hotels within three mins of the Big Day Out venue:
De Vere Horsley Estate
Thatchers Hotel
Within 15 minutes’ drive:
What to wear
West Horsley Place is heated throughout. But it’s a rambling old country pile with flagstone floors on the ground floor, so we’re suggesting you dress for cosy toes and tops (and – what’s to lose – cosy everywhere really too).
Is West Horsley Place accessible?
The ground floor of the Manor House is wheelchair accessible, with a platform lift to the first floor. If you’d find the short walk – or gravel path – from the car park difficult, let us know when you book and we’ll contact the team at West Horsley to make sure you’re looked after when you arrive.
Book your spot now
A Big Day Out Whodunnit costs £50. But there are limited places, so don’t hang about. To book your spot now, follow this link:
Group bookings
We’ve limited group bookings to five places. If you want to book more than that, email us and we’ll add you to the waiting list.
The near-Dickensian language of a Will doesn’t half make the clarity of its contents harder to grasp, doesn’t it?
And then there’s LPAs, which come with limits that catch you out. Things like what an attorney can and can’t gift, whether they can set up a trust, what happens if the attorney themselves loses capacity.
So if you’re prone to befuddlement – and, let’s be honest, who isn’t? – then tune into this conversation with Shaun Moore, Technical Specialist at Quilter.
Because Shaun joined us for a lunch-hour conversation that’s all about deciphering what wills and LPAs actually say.
But this isn’t about which form to fill in or which portal to log into. It’s a planning conversation about why these documents matter, what they can and can’t do, and what paraplanners need to look out for.
And with pensions becoming vulnerable to IHT, and plenty of plans now out of date, this is the ideal time to revisit both documents.
So during this Assembly we covered
- why pensions coming into the estate means old wills need a second look
- Residence Nil Rate Band (RNRB) pitfalls and old discretionary trusts left over from before the transferable nil rate band
- deeds of variation, and what your options are when a will hasn’t been drafted well
- investment powers in will trusts, including bonds for life tenants, STEP provisions and when the Trustee Act 2000 defaults apply
- the limits on what an attorney can do, including gifting and setting up trusts
- LPAs and discretionary fund management, and the Office of the Public Guardian’s reversed guidance on discretionary fund management (now allowed unless the document says otherwise)
- what happens when an attorney themselves loses capacity, and whether a will can be changed or revoked
What can you expect to take away?
Watch or listen and you’ll gain a clearer idea of the role of wills and LPAs so you can spot the planning opportunities.
Even very experienced paraplanners can trip over obstacles lurking in the shadows of IHT.
So we invited Aegon’s tax and trusts manager, Elaine Cruickshank, to join host, Richard Allum, for an online Assembly to help you dodge the IHT perils.
Over the course of one lunch-hour, Elaine:
- untangles the transferable nil rate band and residence nil rate band, including the detail that trips people up around second marriages and downsizing provisions
- gets into the finer points of gifting exemptions, PETs and CLTs, beyond the seven-year headline
- explains how the inclusion of pensions in estates affects the taper threshold, and what that means for clients close to the £2 million mark
- works through charitable giving and the 36% rate, including the added complications once pension funds are in the mix
- brings it all together with planning opportunities you can take straight back to your desk
What can you expect to take away?
Watch or listen now and you’ll have a sharper grasp of the IHT detail that’s easy to get wrong. Plus the confidence to spot these issues in your own client cases.
Watch or listen now
Missed it? Then follow the links below to download Elaine’s slides, watch the replay or catch up with the podcast now.
The outstanding questions
There were so many questions on this Assembly that we ran out of time, so Elaine has provided us with the answers to the outstanding questions, as well as provide a clarification on the final question of the Assembly.
Can the small gifts exemption and the annual £3,000 exemption be given to the same recipient?
If a gift in excess of the £250 small gifts exemption is made, then as this gift is more than the small gifts exemption, the full gift would be allocated against the annual exemption (assuming that this was available).
Why is it called Inheritance Tax? Shouldn’t it be called Estate Tax, as it is (normally) the estate that pays?
“Inheritance Tax” is a better reflection of what the tax is intended to cover — rather than simply being a tax on an estate at death, there could also be IHT applying to lifetime transfers.
Is it best to space significant gifts at least 7 years apart then?
Each gift has its own 7-year clock, but whenever a gift is being made you have to consider the cumulative impact of any gifts made in the previous 7 years. If the donor dies within 7 years of a gift, earlier gifts use up the nil-rate band first before later gifts are considered. Making very large gifts close together can therefore increase the IHT exposure of later gifts, if death occurs within 7 years. Taper relief may reduce the IHT on gifts made more than 3 years before death, but it does not reduce the value of the gift itself for nil-rate band purposes.
Does tax-free income from a beneficiary’s pension (where the spouse dies under age 75), either through an annuity or under FAD, count towards regular income when considering gifting out of surplus income?
This is a grey area and will probably require a tax case to provide clarification. As this money is completely exempt from income tax, HMRC could view the regular withdrawals of this nature as capital rather than income.
Is there a length of time for the ‘main residence’ qualification to be lost?
For the Residence Nil Rate Band, there is no specific minimum or maximum period between the property ceasing to be the deceased’s main residence and their death. The key point is that the property must have been a qualifying residential interest, meaning a property that the deceased occupied as a residence at some point during their ownership. For the downsizing addition, they have to downsize or dispose of the property on or after 8 July 2015, but there is no stipulated timeframe between the date of downsizing/disposal and death.
What if they still own the property but have also moved into a care home?
A property can qualify even if the individual was living in a care home at death, provided the property had been their main residence at some point and they leave the property to their direct descendants. The amount of residence nil rate band available will generally be the lower of the available RNRB and the value of the qualifying residential interest passing to direct descendants, and it may also be reduced by the taper reduction if the estate exceeds £2 million.
If they own a house worth less than the RNRB, should they upsize to make the most of it?
If they upsize and buy a bigger house, the value of the estate would generally remain unchanged — they now have a larger property and less cash. However, if they live in the bigger property as their main residence and leave this to their direct descendants in their will, then they could in theory qualify for the full residence nil rate band if the value of the house was equal to or higher than the residence nil rate band and the £2,000,000 tapering threshold was not breached. However, tax mitigation isn’t the only factor to consider here — there would be the costs of moving house, larger council tax and utility bills etc, which could be more significant than any IHT saving achieved.
Can RNRB apply to an IIP trust, where some people have moved their home into a solicitor’s trust and continued to live in it?
It sounds as though this type of arrangement would potentially be a gift with reservation of benefit, with the value of the property remaining in their IHT estates. Whether or not the RNRB would apply in this scenario would depend on the provisions of the trust. Are the direct descendants the beneficiaries of the trust, and do the trust provisions meet the conditions of ‘directly inheriting’ the property?
Trusts used to be the kind of thing you’d come across every now and again. Something to dust off the knowledge for, handle carefully, then put back on the shelf.
That’s changing. With pension IHT changes on the horizon, trust planning is becoming a regular fixture on paraplanners’ desks and the paraplanners best placed to support their clients will be the ones who can approach it with genuine confidence, not just familiarity.
This Assembly is designed to help you get there.
This practical Assembly takes you from the foundations right through to real-world trust planning decisions.
Shaun Moore, Tax and Financial Planning Expert at Quilter, joins host Richard Allum for this Assembly. Together they work through the essentials and the less obvious bits that every paraplanner working with trusts needs to have at their fingertips.
During this Assembly, we:
- explore why trust planning has moved from the occasional to the everyday, and why the pension IHT changes expected from April 2027 are likely to accelerate that further
- get to grips with the types of trust you’re most likely to encounter (loan trusts, discounted gift trusts and reversionary interest trusts) and how to tell them apart when different providers call them different things
- use the three circles of access, flexibility and tax efficiency as a practical framework for matching the right trust to the right client
- explore the common mistakes and questions that come up again and again
- understand the ongoing practical obligations that come with trusts, from the Trust Registration Service to trustee bank accounts, and when a professional trustee makes sense
What can you expect to take away?
You’ll leave with a clearer, more confident grasp of trust planning, not just the theory, but the practical judgement to apply it. Whether you’re doing in-depth trust research or writing up recommendations that involve one, this session gives you a framework and a reference point you can keep coming back to.
Think about the last time you worked on a financial plan for a family with a child or adult with special educational needs or a disability (SEND). How confident were you that the plan truly reflected what that family needs, not just now, but for the long term?
As paraplanners, we’re in a position to make a real difference but only if we understand what good planning for these families actually looks like.
So in this Assembly first-time host Peter Spence from Fintuity was joined by Ali Fanshawe and Rhiannon Gogh, co-founders of SENDA who are specialists who work with financial and legal advisers to deliver safer, smarter planning for SEND families.
All three participants have children with SEND needs.
What the Assembly covers
Together, Peter, Ali and Rhiannon talked about what special needs planning really involves, where traditional advice tends to fall short, and what paraplanners can do to fill that gap.
The conversation covers:
- how many families are affected in the UK and what the financial planning picture looks like for them on a personal level
- an exploration of the consequences of getting financial planning wrong for families with SEND needs
- the key problems that can crop up during a financial planning process compared to a regular advice process
- the training and support that’s available if you want to develop your knowledge
What can you expect to take away?
By tuning into this Assembly, you’ll get a clearer sense of where special needs planning is different and what to start thinking about when planning for SEND needs. It’s an introduction to the subject rather than a complete guide. But it’s a great primer which offers practical ideas you can use right now. Ideas that will give confidence about doing the right thing for clients whose plans need to take account of family members with special educational needs and disabilities.
The tax landscape has shifted significantly over the past couple of years. Allowance reductions, rising dividend tax rates and the proposed extension of IHT to unused pensions means there’s plenty for paraplanners to get to grips with — and plenty of opportunity to add real value for clients.
This Assembly cuts through the complexity and gives you a clearer picture of how different tax wrappers work in practice, so you can make more confident decisions about which solution is right for which client.
Host, Richard Allum is joined by Elaine Cruickshank, tax and trusts manager at Aegon for a practical, no-nonsense look at onshore bonds, offshore bonds, GIAs and trust solutions with an agnostic perspective that keeps the focus firmly on what’s best for the client in front of you.
What we explored
We looked at how recent tax changes are prompting advisers and paraplanners to revisit wrapper choice, and went through the kind of comparative thinking that helps you work out when a bond might be preferable to a GIA or when onshore makes more sense than offshore.
We also looked at how onshore bonds are actually taxed (including a common misconception that’s worth clearing up), which wrapper tends to suit which client circumstances, and how trust solutions fit into the picture, particularly in the context of the proposed IHT changes to pensions.
What can you expect to take away?
After catching up on the Assembly, you’ll have a clearer understanding of the tax treatment of different wrappers, a more confident sense of when each option is likely to work best, and some practical frameworks for thinking about trust planning solutions.
We’ve been recording ‘Technically speaking’ sessions with Utmost’s Steve Sayer for a few years now.
And because they offer really crunchy case-study based content, they’re really popular with paraplanners.
But we like to plan ahead so late last year, we sat down with Steve and the team at Utmost to talk about the ‘Technically speaking’ plans for 2026. During the conversation, Steve talked about each of the major tax planning milestones that stem from the measures announced by the Chancellor since October 2024 and stretch ahead to 2031.
And when Steve revealed that he had a single slide that set out each of the changes against a timeline, we decided – there and then – that was definitely something paraplanners would like to hear more about.
So we invited Steve into the studio to talk us through it.
And here’s the result: Steve Sayer’s guide to the tax change timeline until April 2031. In it, Steve covers inheritance tax and the domicile regime, excluded property trusts and the new foreign income and gains regime, the agricultural and business property relief changes, pension death benefits in 2027, plus the effects of the freezing of tax bands until 2031.
Plus you can download his slide using the link below.
Pensions will become subject to inheritance tax (IHT) from April 2027, but how much of a role does protection play in your approach to building IHT strategies for your clients? And how confident are you about the protection options that are available to you?
But with IHT receipts expected to almost double, and sweeping changes to business and agricultural property relief already landing from April 2026, paraplanners can expect more and more clients to want to explore all the options.
So at this Assembly, host Richard Allum was joined by Alan Jenkinson, protection specialist at Scottish Widows, to walk through the essentials. During their lunch-hour discussion, Richard and Alan unpack IHT and how it works, run through the key exemptions and reliefs, and explore how protection fits into an IHT planning conversation alongside gifting strategies, trust structures and the normal expenditure out of income rules.
There’s also a really useful section on the underwriting process: what to do when a client has health risk factors, when concurrent applications make sense, and why a declined application isn’t necessarily the end of the road.
If you’re looking for a solid grounding in this area — or a practical refresher before your next client review — this one’s well worth an hour of your time.
The Government’s Finance Bill which includes the provision for pensions to become subject to inheritance tax (IHT) has reached a critical point in its progress through Parliament.
But as James Jones-Tinsley of Barnett Waddingham explains in this 15-minute briefing recorded especially for the Paraplanners’ Assembly, the measure isn’t necessarily a done deal.
Why the next few weeks matter
He suggests that the government’s recent decision to raise its proposed threshold on agricultural and business property relief from £1 million to £2.5 million indicates that the government can be persuaded to rethink its plans.
So the next few weeks matter. And that’s why James is encouraging advice professionals and clients to write to their MPs – not least to encourage the government to consider the practical consequences of its planned changes.
For instance, how reasonable and realistic is it to expect personal representatives, many who are likely to be recently bereaved family members, to successfully negotiate their way through complex pension death benefit rules against the clock?
And is adding to the anxiety of family members worth it when the government’s own projections suggest this will raise £1.5 billion by 2029-30 – a fraction of the £6 billion that is already being collected thanks to freezing of allowances?
What you’ll learn by watching and listening
If you want to know the latest on the progress of the law resulting from last November’s budget and its consequence for advice colleagues and clients, then you’re in the right place.It’s more than a year since speculation ahead of last autumn’s Budget led to a surge of savers raiding their pension pots in a bid to beat rumoured changes to tax-free lump sums.
But when no changes were announced and people sought to reverse their withdrawals, they discovered that the 30-day cancellation rule didn’t apply. Or did it?
That confusion over conduct of business rules led to calls for HMRC and the FCA to clarify whether or not savers could cancel – and they’ve now responded.
Budget measures are often the subject of media speculation. But the level of attention in the run-up to the Chancellor of the Exchequer’s Budget statement on 26 November 2025 was unprecedented.
So did the reality match the hype?
For our final Assembly of 2025, we invited Les Cameron from M&G Wealth to join us and share his latest thoughts on what paraplanners need to know following Rachel Reeves’s statement.
Les covers a bunch of different topics that include:
- Inheritance tax changes and business relief updates
- Capital gains tax rates and allowances
- ISA allowances
- Pensions, IHT liability and the role of personal representatives
- Salary sacrifice
- Tax rates, bands and allowances
- Beneficial ordering
- The effect of fiscal drag (or ‘stealth taxes’)
Plus more besides. So if you want to catch up with what’s been announced, what’s changing, or what’s staying the same, this is the Assembly for you.
Assemblies featuring the M&G technical team in 2025
This is the fifth Assembly of the year featuring experts from M&G Wealth’s technical team. Here are the other four from 2025:
February 2025 – Pensions, death and taxes (with Les)
April 2025 – A guide to investment bond essentials for paraplanners (with Barrie Dawson)
August 2025 – Tax wrappers: which, why and when? (with Neil Macleod)
September 2025 – The pension IHT bombshell has landed – now what? (with Les)