Most financial plans treat cancer as a rare event, or as though a diagnosis always means the end of the road.
New joint research from Scottish Widows and Macmillan, tells a different story. By 2045, cancer prevalence in the UK is forecast to rise by 58%, taking the number of people living with or beyond cancer to 5.4 million and survival rates have doubled in the last forty years. So, cancer is no longer the death sentence it once was, and that changes what financial planning needs to do.
That’s why we invited Scottish Widows national account manager, Jonathan Hall, to join host Richard Allum and talk through what the research means and help paraplanners understand what it might mean to their day-to-day paraplanning.
John unpacks what’s driving the increase (an ageing population, earlier diagnosis through screening, and improving survival rates), and what it means for clients at every stage: building cash flow models that stress test a plan against a cancer diagnosis, why premiums for the same cover roughly triple by your thirties and more than double again by your forties, and how needs shift from a client in their twenties protecting a lifestyle to one in retirement assuming their savings will simply see them through.
Tune in now to find out how to bring this conversation to life for your clients.
What can you expect?
- the numbers behind a forecast 58% rise in UK cancer prevalence by 2045, and what’s driving it
- how to use cash flow modelling to bring a “what if” conversation to life for clients
- how protection needs and objections shift across generations, from Gen Z to those approaching retirement
- why “I’ve already got cover” and “I’ve got savings to fall back on” are worth gently challenging
- how protection can work as an intergenerational planning tool, including for clients’ adult children
Request a CPD certificate and download Jonathan’s slides
Once you have watched or listened to this episode, you can request a certificate of attendance for 35 minutes’ CPD. To do that, follow the link below where you will also be able to download Jonathan’s slides.
The Autumn Budget lands on 28 October. A week later, we’re sitting down with someone who’ll have properly thought it through.
Les Cameron from M&G joins Richard Allum to unpack what the Budget actually means, for clients, for financial plans, and for paraplanners.
Les needs no introduction in paraplanning circles, and this is your chance to hear his take before you’re the one fielding the questions.
- What the Budget changes (and what it doesn’t)
- The practical implications for planning
- What paraplanners should be thinking about next
There will be CPD available.
Have you ever stopped to think about the assumptions baked into a fact find? A tickbox for “marital status.” A question about “your wife” or “your husband.” A box that asks for “gender” with only two options to choose from. A form that only makes room for children who are biologically yours.
These assumptions, and experiences of LGBTQ+ clients raise some important considerations for financial planning and, as paraplanners, we are well placed to make sure the file and the advice reflects who the client actually is, not who they’re assumed to be.
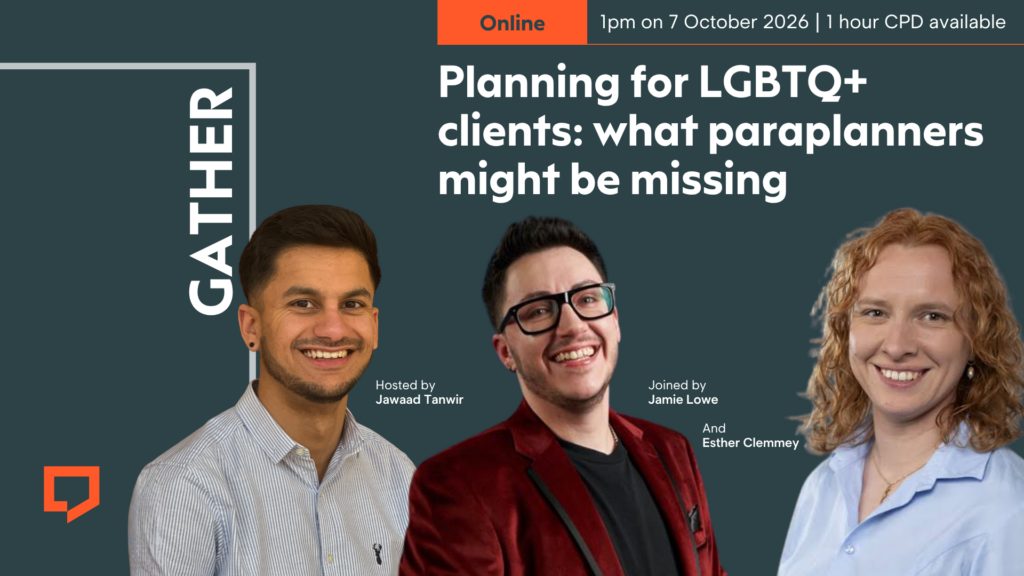
Join us at 1.00pm on Wednesday 7 October as we explore what paraplanners may be unintentionally overlooking when working with LGBTQ+ clients, and how to build a process where those clients feel understood without ever having to justify who they are.
Jawaad Tanwir, of ParaplanX is hosting this conversation and is joined by Esther Clemmey of Integrity365 and Jamie Lowe of True Self Wealth.
Together, they’ll look at where assumptions most often creep into the advice process – about marriage, gender, children, beneficiaries and “chosen family” – and the practical planning issues that follow including: Wills and intestacy for unmarried couples, pension nominations, protection underwriting, international planning, and later-life concerns about who gets recognised as next of kin.
During this Assembly we expect to
- understand what paraplanners may unintentionally overlook when working with LGBTQ+ clients
- explore the practical planning issues that can arise
- consider how to build a process in which LGBTQ+ clients feel understood, without making assumptions
Sound like something you’d like to know more about? Save your spot now.
A Kerr-Fuffell family member has snuffed it. But was it foul play? Join paraplanner sleuths to sift for clues and crack the case.
You’re invited to a Big Day Out with a difference.
Because we’d love you to gather with paraplanners from across the UK at West Horsley Place in Surrey from 9am on Tuesday 3 November 2026.
Over the course of the day, you’ll work out which member of the Kerr-Fuffell family stood to gain most from the untimely demise of their (perhaps not so) loved one.
Our writers room of supremely well-qualified paraplanners is busily concocting a series of – fingers crossed – interconnected case studies.
Inheritance tax, pensions, estate planning, wills, lasting powers of attorney, divorce, protection – you name it – we’ll cram it in.
In other words, you’re guaranteed an agenda that will be bursting at the seams with seven hours’ worth of CPD. That’s knowledge and insights that you can apply to client cases right away.
How will the day work?
At 10am, we’ll gather in the Great Hall for your briefing on the untimely demise of Lady Fifi.
Then you’ll join one of four groups, each led by a duo of paraplanning detectives.
In a series of sessions, your group will meet with expert witnesses drawn from our supporters – that’s Aegon, Howden, M&G, Quilter, Scottish Widows, Transact and Wealthtime – to sift evidence contained in case studies.
Whoa there! Why does West Horsley Place look familiar?
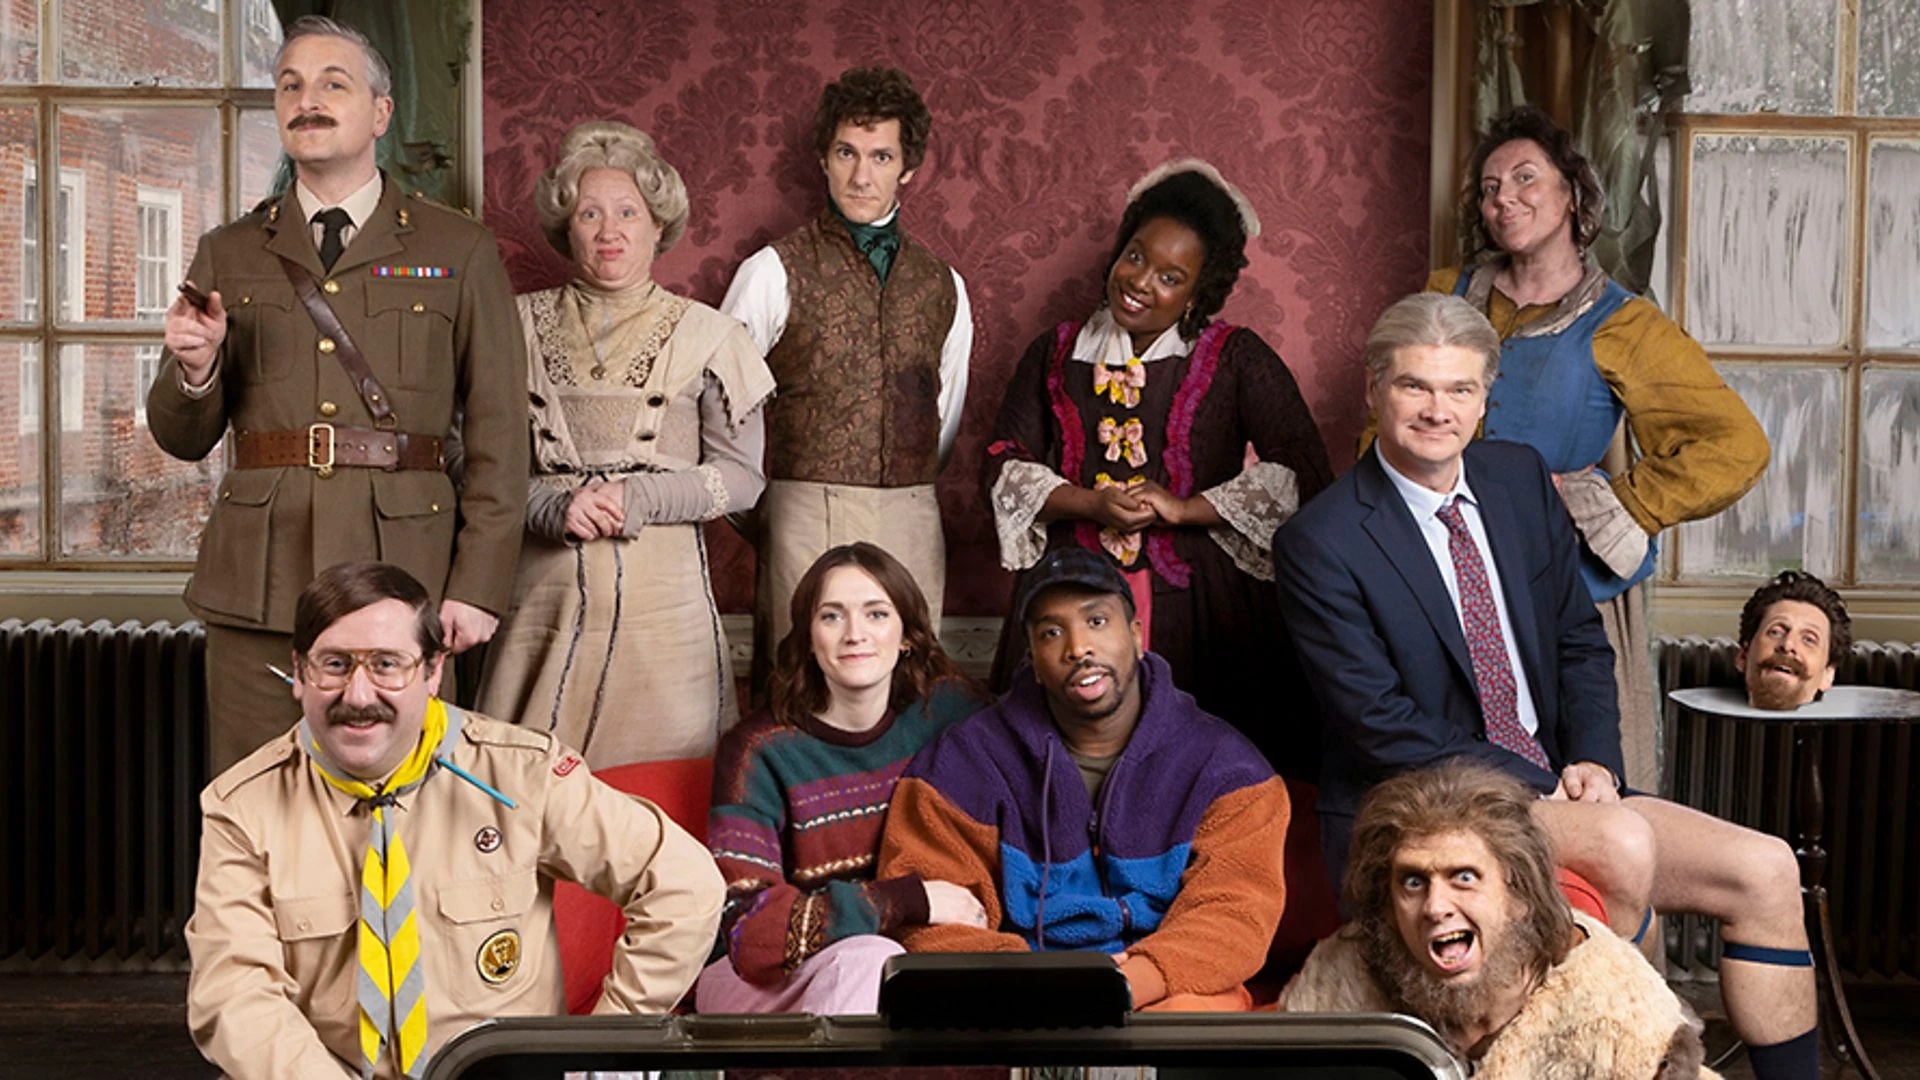
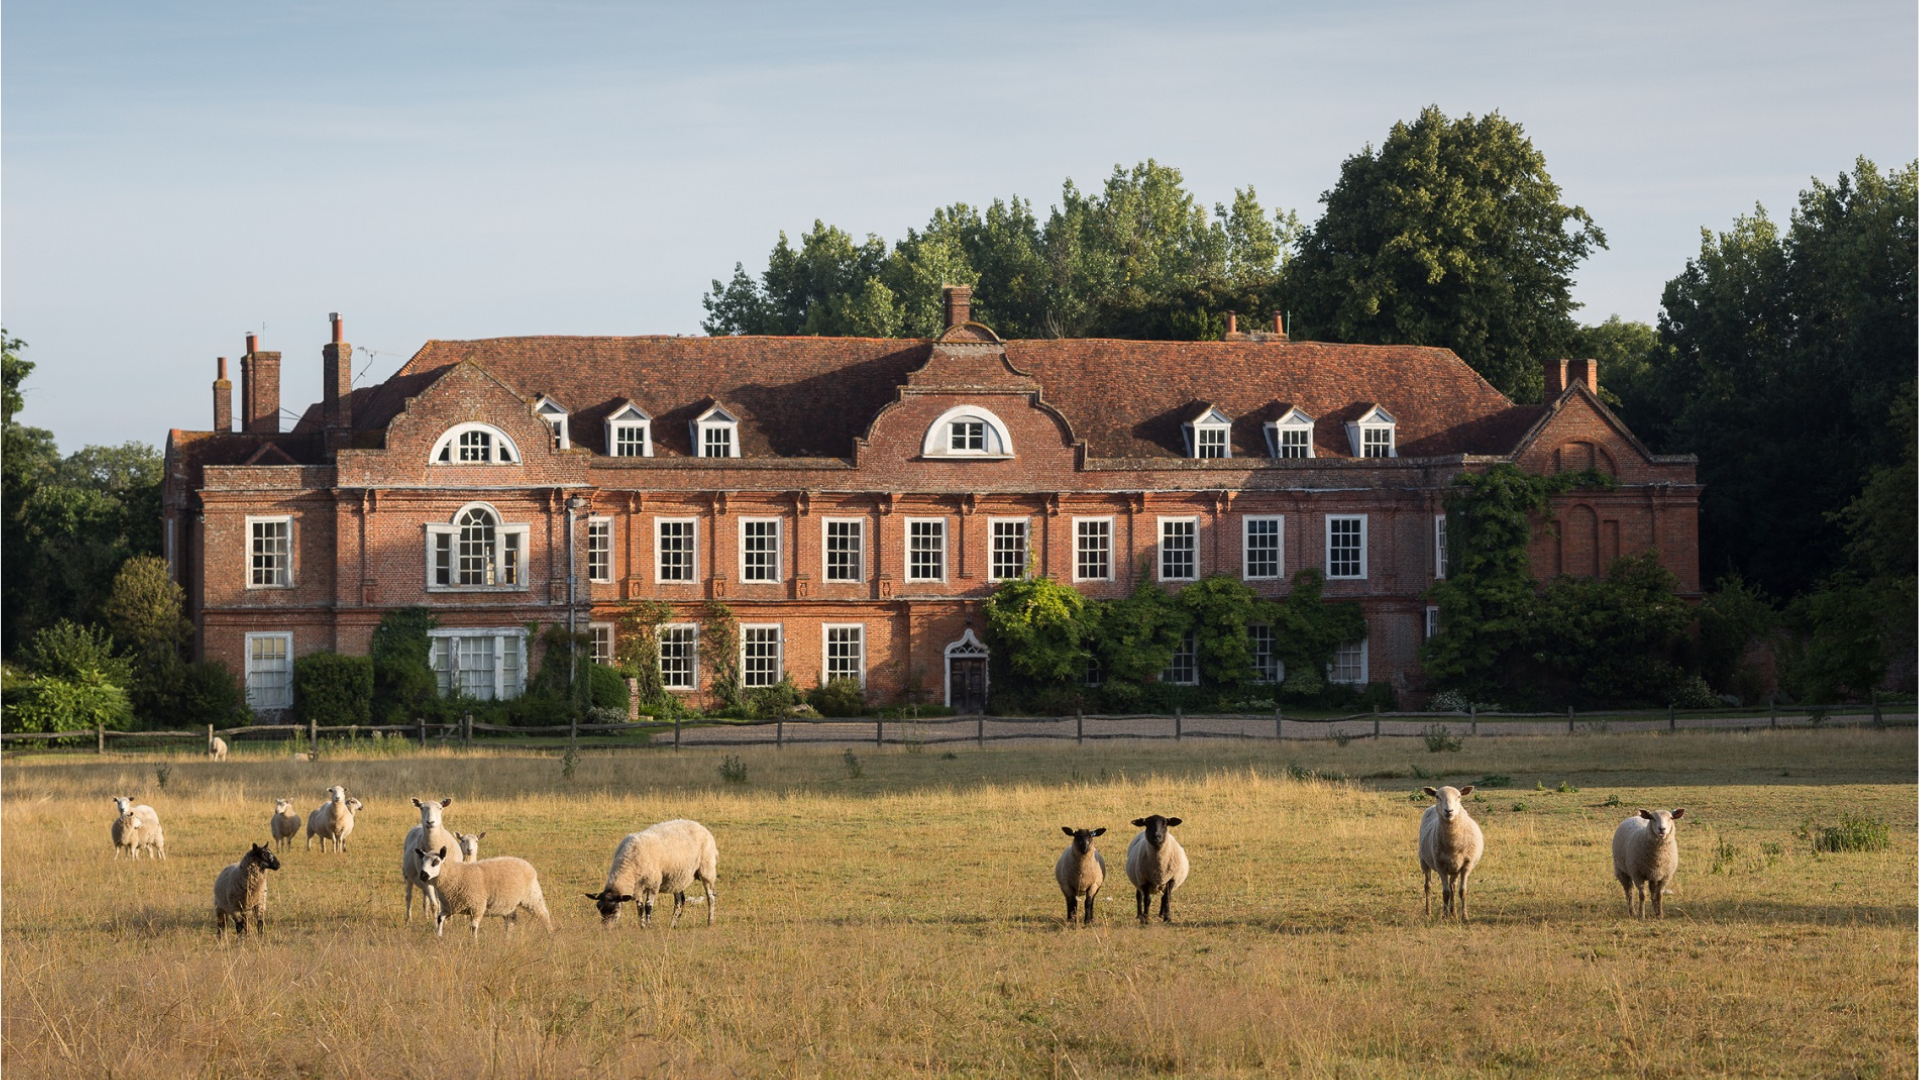
If you’re a fan of the hit BBC TV comedy ‘Ghosts’, it will.
Because West Horsley Place is Button House!
And do you know what? It looks EXACTLY like it does on the telly – outside and in.
So not only will you get to take part in the Big Day Out, you can sneak a few selfies in the Great Hall, the library, that long red room upstairs, the grand staircase, the garden, even the corridor that leads to the plague pit.
What’s more, we’ll take the traditional ‘school photo’ in front of house.
How exciting is that?!
And in a happy coincidence, we’ll be gathering for our Big Day Out just one week after ‘Ghosts: The Possession of Button House’ is released in UK cinemas.
Will you feed me?
This is a Paraplanners’ Assembly event, so we won’t scrimp on the catering.
Your ticket includes breakfast baps (or butties) on arrival, a delicious hot buffet lunch, plus a sweet treat with your tea in the afternoon.
There will be vegetarian and vegan options. And if there are ingredients you need to be careful of, let us know when you book, and we’ll take care of that.
Surrey? But that’s far far away!
It’s a fair cop. For 12 years we’ve hosted events in the Midlands-ish, so it was reasonably easy for people to get to.
But getting exclusive use of a country estate for a whole day’s Whodunnit that’s just the right size for a Big Day Out – well, that’s quite tricky.
Being big ‘Ghosts’ fans, when we discovered we could have Button House to ourselves for the day, we couldn’t resist.
We know Surrey is a stretch. And if that means you don’t feel able to join us this year, we’ll make it up to you next year. Promise.
Getting there
By car: West Horsley Place is off the A246 between Guildford and Leatherhead. It’s ten minutes’ drive from the A3/M25 intersection. Leave the A3 at junction 10. You can park for free in the visitor car park.
By train: Horsley station is one mile away, with frequent trains from London Waterloo (49-minute journey), Vauxhall, Clapham Junction and Guildford (14-minute journey). Woking station is 8 miles away, with frequent, fast trains to and from London. It takes about 25 minutes to walk from the station to West Horsley Place. It is a lovely walk through the estate, but you will need footwear suitable for wet, muddy or uneven ground. Follow the bridleway and you’ll arrive in the car park and welcome area.
By bus: The 479 Guildford-Bookham-Leatherhead-Epsom service operates roughly hourly. The nearest stop is East Horsley, Duke of Wellington. It takes approximately 7 minutes to walk from the stop. The entrance to West Horsley Place is on the right before you reach St Mary’s Church. Walk down the drive to reach the Welcome Area next to the Barn.
Here’s the bus timetable: Service 479
Where to stay
West Horsley Place has plenty of places to stay. There are two large hotels within three mins of the Big Day Out venue:
De Vere Horsley Estate
Thatchers Hotel
Within 15 minutes’ drive:
What to wear
West Horsley Place is heated throughout. But it’s a rambling old country pile with flagstone floors on the ground floor, so we’re suggesting you dress for cosy toes and tops (and – what’s to lose – cosy everywhere really too).
Is West Horsley Place accessible?
The ground floor of the Manor House is wheelchair accessible, with a platform lift to the first floor. If you’d find the short walk – or gravel path – from the car park difficult, let us know when you book and we’ll contact the team at West Horsley to make sure you’re looked after when you arrive.
Book your spot now
A Big Day Out Whodunnit costs £50. But there are limited places, so don’t hang about. To book your spot now, follow this link:
Group bookings
We’ve limited group bookings to five places. If you want to book more than that, email us and we’ll add you to the waiting list.
Temporary pension income guarantees are nothing new to retirement income planning. But how much do you actually know about how they work?
During this Online Assembly, Richard Allum and M&G’s Mark Devlin take a practical look at temporary pension income guarantees, and what they mean for cases that you may work on.
During this Assembly, Mark explained:
- what temporary guarantees are and how they work
- the options available to clients
- what happens to death benefits
- why you might consider using them in a client’s retirement plan
Plus they added a couple of real-world case studies into the mix to bring it all to life.
What can you expect to take away?
A clearer, more practical understanding of temporary pension income guarantees, and a sense of when and why they might be worth putting in front of a client.
Ready to top up your knowledge? Catch up now.
The near-Dickensian language of a Will doesn’t half make the clarity of its contents harder to grasp, doesn’t it?
And then there’s LPAs, which come with limits that catch you out. Things like what an attorney can and can’t gift, whether they can set up a trust, what happens if the attorney themselves loses capacity.
So if you’re prone to befuddlement – and, let’s be honest, who isn’t? – then tune into this conversation with Shaun Moore, Technical Specialist at Quilter.
Because Shaun joined us for a lunch-hour conversation that’s all about deciphering what wills and LPAs actually say.
But this isn’t about which form to fill in or which portal to log into. It’s a planning conversation about why these documents matter, what they can and can’t do, and what paraplanners need to look out for.
And with pensions becoming vulnerable to IHT, and plenty of plans now out of date, this is the ideal time to revisit both documents.
So during this Assembly we covered
- why pensions coming into the estate means old wills need a second look
- Residence Nil Rate Band (RNRB) pitfalls and old discretionary trusts left over from before the transferable nil rate band
- deeds of variation, and what your options are when a will hasn’t been drafted well
- investment powers in will trusts, including bonds for life tenants, STEP provisions and when the Trustee Act 2000 defaults apply
- the limits on what an attorney can do, including gifting and setting up trusts
- LPAs and discretionary fund management, and the Office of the Public Guardian’s reversed guidance on discretionary fund management (now allowed unless the document says otherwise)
- what happens when an attorney themselves loses capacity, and whether a will can be changed or revoked
What can you expect to take away?
Watch or listen and you’ll gain a clearer idea of the role of wills and LPAs so you can spot the planning opportunities.
Are you an outsourced paraplanner?
Whether you’re the only employee of your paraplanning practice, or you lead a paraplanning powerhouse with employees and a hefty bank of clients, outsourced paraplanners share lots of things in common.
You just do.
But here’s the thing: despite the growing number of outsourced paraplanners in the UK these days, opportunities to get together to talk only about things that matter in the outsourced world, are surprisingly few and far between.
Switch off. Show up. Join in.
So, if you’re an outsourced paraplanner, here’s our invitation: at 1pm on Thursday 29 October 2026, set your notifications to ‘do not disturb’, click on the Zoom link in your event invitation and gather with other outsourced paraplanners across the UK for an hour of conversation, ideas and practical insights.
There’s nothing to prepare.
We’re starting this Assembly discussing fees and see where it goes from there.
Spaces are limited. To save a spot hit ‘Book Event’ and look out for the calendar invitation in your inbox.
Would you trust a fun fact you can’t find in black and white?
That’s just one of the questions rattling around in this episode – the first-ever podcast-only instalment of the Self-Assembly Paraplanning Show. It’s a regular, unscripted conversation where a small group of paraplanners compare notes on what’s actually happening in their world.
This episode’s host Sam Tonks, is joined by Julie South, who runs outsourced paraplanning business, Bee Paraplanning, and Steven McBurnie, a Senior Associate at RBC Brewin Dolphin and is currently on the pathway to becoming client-facing.
Across the hour they cover:
- when is a ‘fun fact’ actually ‘fact’? How do you know and why does it matter?
- CPD opportunities hiding in plain sight – why “research before a case” counts as CPD
- AI in paraplanning – where it genuinely helps (source-checking, drafting) and why it hasn’t replaced the trust between adviser and paraplanner
- GP records, data silos, and why medical underwriting keeps stalling protection cases, and the wider frustration of providers who won’t pick up the phone
- smart glasses, meeting recording, and where data collection starts to feel like too much
- clients turning up to meetings having already run their suitability report through ChatGPT or Copilot
The episode wraps up with events for your diary and some very unfinancial recommendations for the Summer holidays.
Even very experienced paraplanners can trip over obstacles lurking in the shadows of IHT.
So we invited Aegon’s tax and trusts manager, Elaine Cruickshank, to join host, Richard Allum, for an online Assembly to help you dodge the IHT perils.
Over the course of one lunch-hour, Elaine:
- untangles the transferable nil rate band and residence nil rate band, including the detail that trips people up around second marriages and downsizing provisions
- gets into the finer points of gifting exemptions, PETs and CLTs, beyond the seven-year headline
- explains how the inclusion of pensions in estates affects the taper threshold, and what that means for clients close to the £2 million mark
- works through charitable giving and the 36% rate, including the added complications once pension funds are in the mix
- brings it all together with planning opportunities you can take straight back to your desk
What can you expect to take away?
Watch or listen now and you’ll have a sharper grasp of the IHT detail that’s easy to get wrong. Plus the confidence to spot these issues in your own client cases.
Watch or listen now
Missed it? Then follow the links below to download Elaine’s slides, watch the replay or catch up with the podcast now.
The outstanding questions
There were so many questions on this Assembly that we ran out of time, so Elaine has provided us with the answers to the outstanding questions, as well as provide a clarification on the final question of the Assembly.
Can the small gifts exemption and the annual £3,000 exemption be given to the same recipient?
If a gift in excess of the £250 small gifts exemption is made, then as this gift is more than the small gifts exemption, the full gift would be allocated against the annual exemption (assuming that this was available).
Why is it called Inheritance Tax? Shouldn’t it be called Estate Tax, as it is (normally) the estate that pays?
“Inheritance Tax” is a better reflection of what the tax is intended to cover — rather than simply being a tax on an estate at death, there could also be IHT applying to lifetime transfers.
Is it best to space significant gifts at least 7 years apart then?
Each gift has its own 7-year clock, but whenever a gift is being made you have to consider the cumulative impact of any gifts made in the previous 7 years. If the donor dies within 7 years of a gift, earlier gifts use up the nil-rate band first before later gifts are considered. Making very large gifts close together can therefore increase the IHT exposure of later gifts, if death occurs within 7 years. Taper relief may reduce the IHT on gifts made more than 3 years before death, but it does not reduce the value of the gift itself for nil-rate band purposes.
Does tax-free income from a beneficiary’s pension (where the spouse dies under age 75), either through an annuity or under FAD, count towards regular income when considering gifting out of surplus income?
This is a grey area and will probably require a tax case to provide clarification. As this money is completely exempt from income tax, HMRC could view the regular withdrawals of this nature as capital rather than income.
Is there a length of time for the ‘main residence’ qualification to be lost?
For the Residence Nil Rate Band, there is no specific minimum or maximum period between the property ceasing to be the deceased’s main residence and their death. The key point is that the property must have been a qualifying residential interest, meaning a property that the deceased occupied as a residence at some point during their ownership. For the downsizing addition, they have to downsize or dispose of the property on or after 8 July 2015, but there is no stipulated timeframe between the date of downsizing/disposal and death.
What if they still own the property but have also moved into a care home?
A property can qualify even if the individual was living in a care home at death, provided the property had been their main residence at some point and they leave the property to their direct descendants. The amount of residence nil rate band available will generally be the lower of the available RNRB and the value of the qualifying residential interest passing to direct descendants, and it may also be reduced by the taper reduction if the estate exceeds £2 million.
If they own a house worth less than the RNRB, should they upsize to make the most of it?
If they upsize and buy a bigger house, the value of the estate would generally remain unchanged — they now have a larger property and less cash. However, if they live in the bigger property as their main residence and leave this to their direct descendants in their will, then they could in theory qualify for the full residence nil rate band if the value of the house was equal to or higher than the residence nil rate band and the £2,000,000 tapering threshold was not breached. However, tax mitigation isn’t the only factor to consider here — there would be the costs of moving house, larger council tax and utility bills etc, which could be more significant than any IHT saving achieved.
Can RNRB apply to an IIP trust, where some people have moved their home into a solicitor’s trust and continued to live in it?
It sounds as though this type of arrangement would potentially be a gift with reservation of benefit, with the value of the property remaining in their IHT estates. Whether or not the RNRB would apply in this scenario would depend on the provisions of the trust. Are the direct descendants the beneficiaries of the trust, and do the trust provisions meet the conditions of ‘directly inheriting’ the property?
An odd feature of paraplanning is that quite a bit of our time is spent designing strategies that are all about the inevitability of death but – just like in our everyday lives – lots of our clients seem reluctant to talk about death and dying and being prepared for it.
Yet the financial grief that families and friends face following a death serves only to compound the overwhelming emotional kind.
That’s what this Assembly is all about. Kylie Clark of Wealthtime, Katy Hancock of Dorothy House Hospice Care and Lucy Halliday from Argonaut Paraplanning joined Richard Allum to talk about death and dying.
Because at a time when a growing percentage of clients are reaching an age when they should be dotting the i’s and crossing the t’s in plenty of time before they die, what can paraplanners do to help them get death-ready?
What you’ll learn
- Out-of-date expression of wish forms, account and app passwords, overseas accounts, tracking down former advisers and solicitors – what are the biggest and most frequent problems following death? And what can clients and their families do to avoid them?
- The way firms handle bereavement is one of the most significant sources of complaints across financial services. With bereavement support about to come under the FCA’s spotlight, what can advice practices do to improve things?
- Learn how the ‘last 1,000 days’ concept could offer a lens to help clients and their families plan
- Grief isn’t just the client’s, it’s the paraplanner’s too. How we’ve been able to acknowledge grief in the past influences how we’re able to help clients experiencing it now and in the future.
Watch or listen now
Paraplanners from all across the UK got together to share ideas, ask questions and break the big taboo about death. Plus there’s one hour’s CPD available.
Missed it? Then follow the links below and watch the replay or catch up with the podcast now.