In the second of our occasional ‘Ask Adam’ Assemblies, we’re joined by Adam Cole, retirement specialist at Quilter, to dig (even) deeper into some of the trickier corners of pensions.
Join us online at 1.00 pm on Wednesday 2 December to put your pension questions to Adam – and his colleague Susie who will be in the chat.
Never knowingly underprepared, Adam and host Richard Allum will be ready to discuss:
- GMPs: what a guaranteed minimum pension is and what it means for the advice
- Annuities: the main types and options, what’s available to dependants, nominees and successors, and the difference between spouse’s and non-spouse joint life annuities
- Annuity death benefits and IHT: how death benefits are calculated and taxed where there’s a guarantee period or a dependant’s pension, which matters more now that some are looking at buying annuities with long guarantee periods and gifting from surplus income
- Care annuities: can a pension fund buy an immediate needs care annuity?
- The state pension: how the old basic and SERPS compare with the new flat rate, state pension age and the upcoming third review, a quick look at the triple lock, what can be inherited, what happens on death and divorce, common misunderstandings, and what can be done about a shortfall, including voluntary contributions and the time limits
- Safeguarded benefits: what they are, how they affect transfers, and the permissions advisers need
- The minimum pension age change: what’s coming and what we should be thinking about now
- Pensions and IHT in practice: you’re no doubt across the legislation but what will actually happen when someone dies after April 2027? Adam will share where things stand on process, plus best practice on death benefit nominations
And if there’s time, we’ll look at pensions dashboards, including what the dashboard will (and won’t) show, who can access it, and how it could help at the fact-find stage.
Missed the first Ask Adam? You can catch up here on the recording or the podcast before 2 December.
CPD is available for this Assembly.
Ready to brush up your pensions know-how? Save your spot now.
Every year, Scottish Widows survey UK paraplanners to find out how they’re feeling about their work and the changes shaping the profession. And every year, Scottish Widows give the Paraplanners’ Assembly an advance look at what they’ve discovered, before the results are published.
IHT, AI and the future of paraplanning
On 22 October, Harry Keating-Coyne, Intermediary Distribution Manager at Scottish Widows, joined us to discuss the emerging themes from this year’s survey.
IHT: the big story
It’s no surprise that the April 2027 changes bringing pensions into the IHT net are a big shift for advice firms and their clients. But the survey shows it might be a bigger shift than some first currently realise. The research looks closely at how prepared the profession is, including:
- how ready paraplanners feel for the changes
- what firms have already changed or are in the process of changing
- how client conversations and planning strategies are changing
- potential product implications and unintended consequences
- whether they could spark broader intergenerational and whole family planning
AI and the future of advice
Richard and Harry look at what paraplanners and advisers think about AI, Targeted Support and simplified advice. For AI, this covers how far firms are adopting it, how confident people feel, and whether it’s seen as an opportunity or a threat.
Richard and Harry talk about the future shape of advice businesses and the role of paraplanners within them. This includes the impact of regulation on workload (a returning theme from previous surveys), recruitment and changing client expectations.
What can you expect?
This is a chance from you to hear what peers are thinking before the full report lands. You’ll get a sense of how your own firm’s approach to IHT and AI compares with others.
The Assembly lasts one hour and CPD is available.
Watch the replay now.
Most financial plans treat cancer as a rare event, or as though a diagnosis always means the end of the road.
New joint research from Scottish Widows and Macmillan, tells a different story. By 2045, cancer prevalence in the UK is forecast to rise by 58%, taking the number of people living with or beyond cancer to 5.4 million and survival rates have doubled in the last forty years. So, cancer is no longer the death sentence it once was, and that changes what financial planning needs to do.
That’s why we invited Scottish Widows national account manager, Jonathan Hall, to join host Richard Allum and talk through what the research means and help paraplanners understand what it might mean to their day-to-day paraplanning.
John unpacks what’s driving the increase (an ageing population, earlier diagnosis through screening, and improving survival rates), and what it means for clients at every stage: building cash flow models that stress test a plan against a cancer diagnosis, why premiums for the same cover roughly triple by your thirties and more than double again by your forties, and how needs shift from a client in their twenties protecting a lifestyle to one in retirement assuming their savings will simply see them through.
Tune in now to find out how to bring this conversation to life for your clients.
What can you expect?
- the numbers behind a forecast 58% rise in UK cancer prevalence by 2045, and what’s driving it
- how to use cash flow modelling to bring a “what if” conversation to life for clients
- how protection needs and objections shift across generations, from Gen Z to those approaching retirement
- why “I’ve already got cover” and “I’ve got savings to fall back on” are worth gently challenging
- how protection can work as an intergenerational planning tool, including for clients’ adult children
Request a CPD certificate and download Jonathan’s slides
Once you have watched or listened to this episode, you can request a certificate of attendance for 35 minutes’ CPD. To do that, follow the link below where you will also be able to download Jonathan’s slides.
The Autumn Budget landed on 28 October. A week later, we sat down with Les Cameron from M&G to unpack what the Budget actually means, for clients, for financial plans, and for paraplanners.
Les needs no introduction in paraplanning circles, and this is your chance to hear his take on:
- What the Budget changes (and what it doesn’t)
- The practical implications for planning
- What paraplanners should be thinking about next
CPD is available.
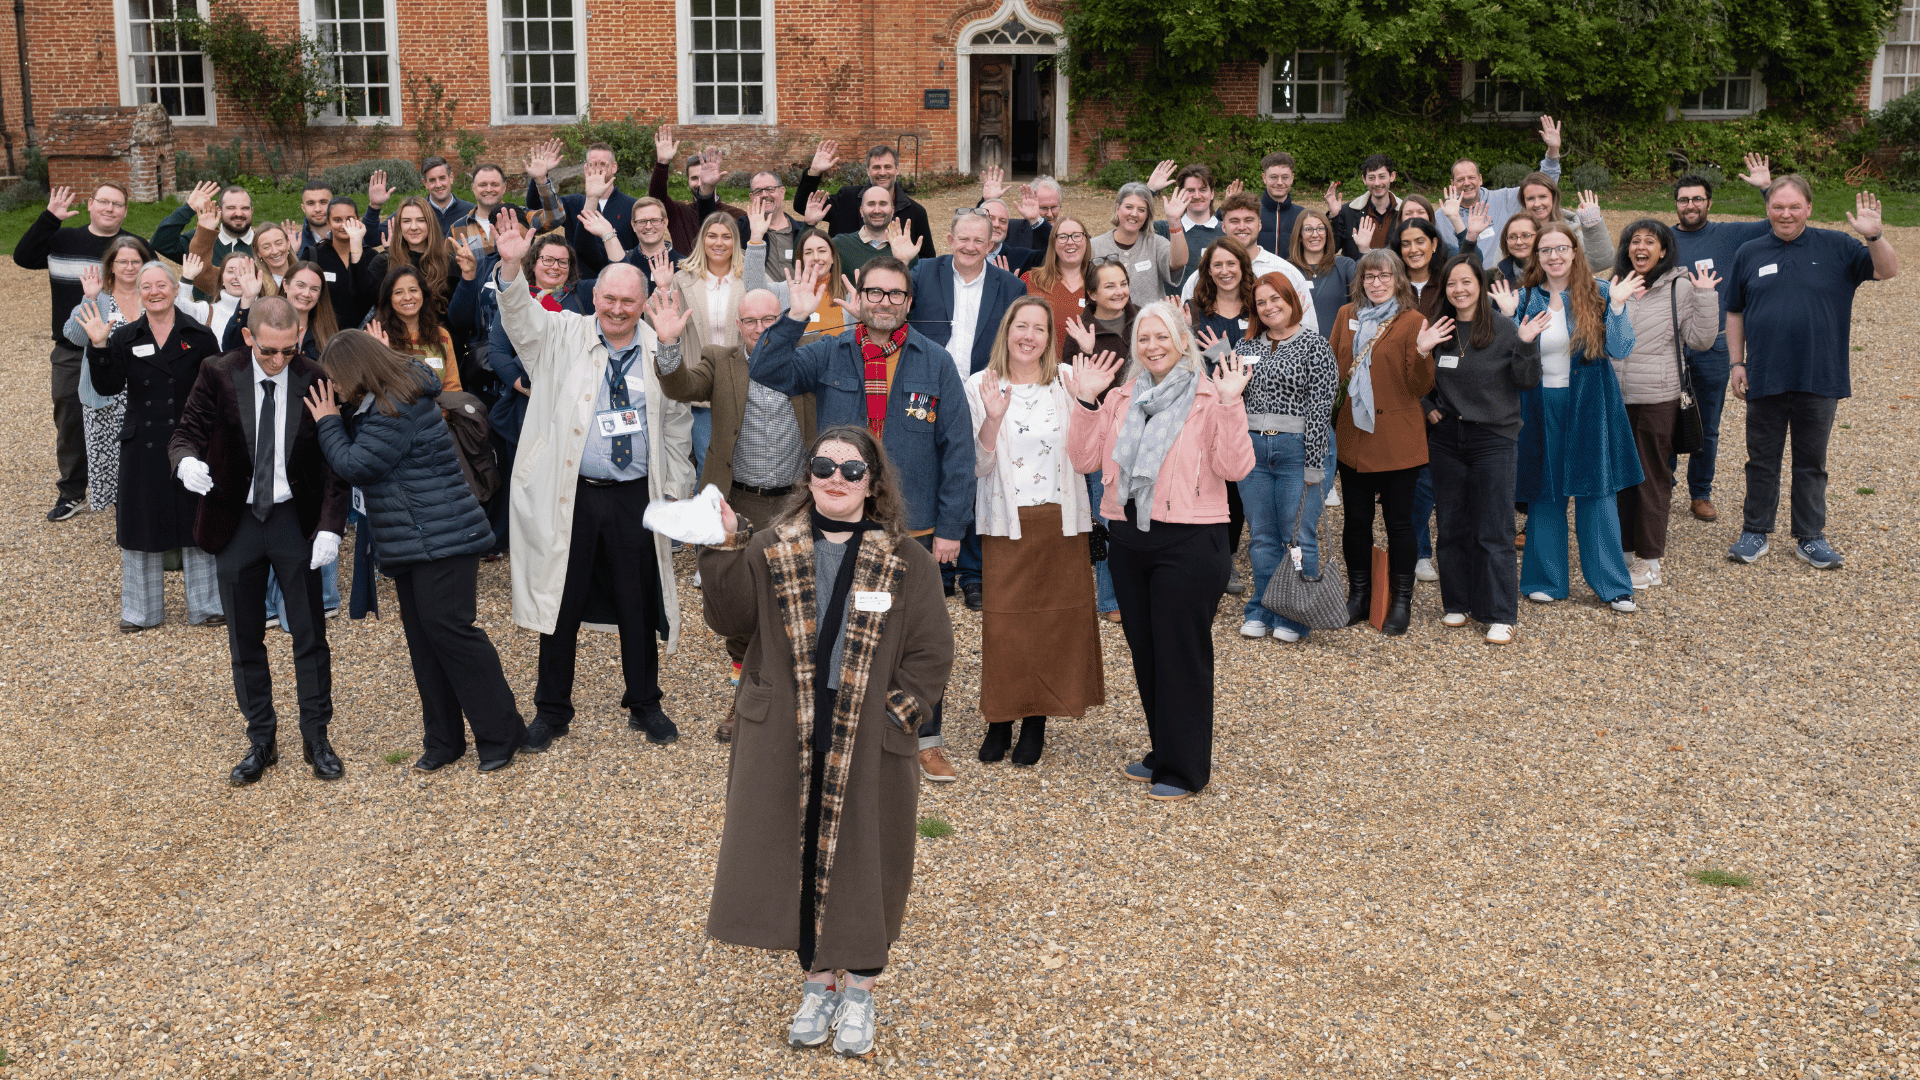
A Kerr-Fuffell family member has snuffed it. But was it foul play? Paraplanner sleuths gathered to sift for clues and crack the case at a Big Day Out with a difference.
Because for our national gathering in 2026, the Assembly invited paraplanners to a Whodunnit at West Horsley Place in Surrey (pictured below) in November 2026.
Over the course of the day, we invited four investigating teams to work out which member of the Kerr-Fuffell family stood to gain most from the untimely demise of their (perhaps not so) loved one.
In a series of sessions, investigating team met with expert witnesses drawn from our supporters – that’s Aegon, Howden, M&G, Quilter, Scottish Widows, Transact and Wealthtime – to sift evidence contained in case studies.
Our writers room of supremely well-qualified paraplanners concocted a pair of interconnected case studies that enabled exploration of inheritance tax, pensions, estate planning, wills, lasting powers of attorney, divorce, pre-nups and and more. That’s knowledge and insights that participants could apply to client cases right away.
It was an immersive technical day bursting at the seams with five hours’ worth of CPD accredited by the LIBF.
Whoa there! Why does West Horsley Place look familiar?
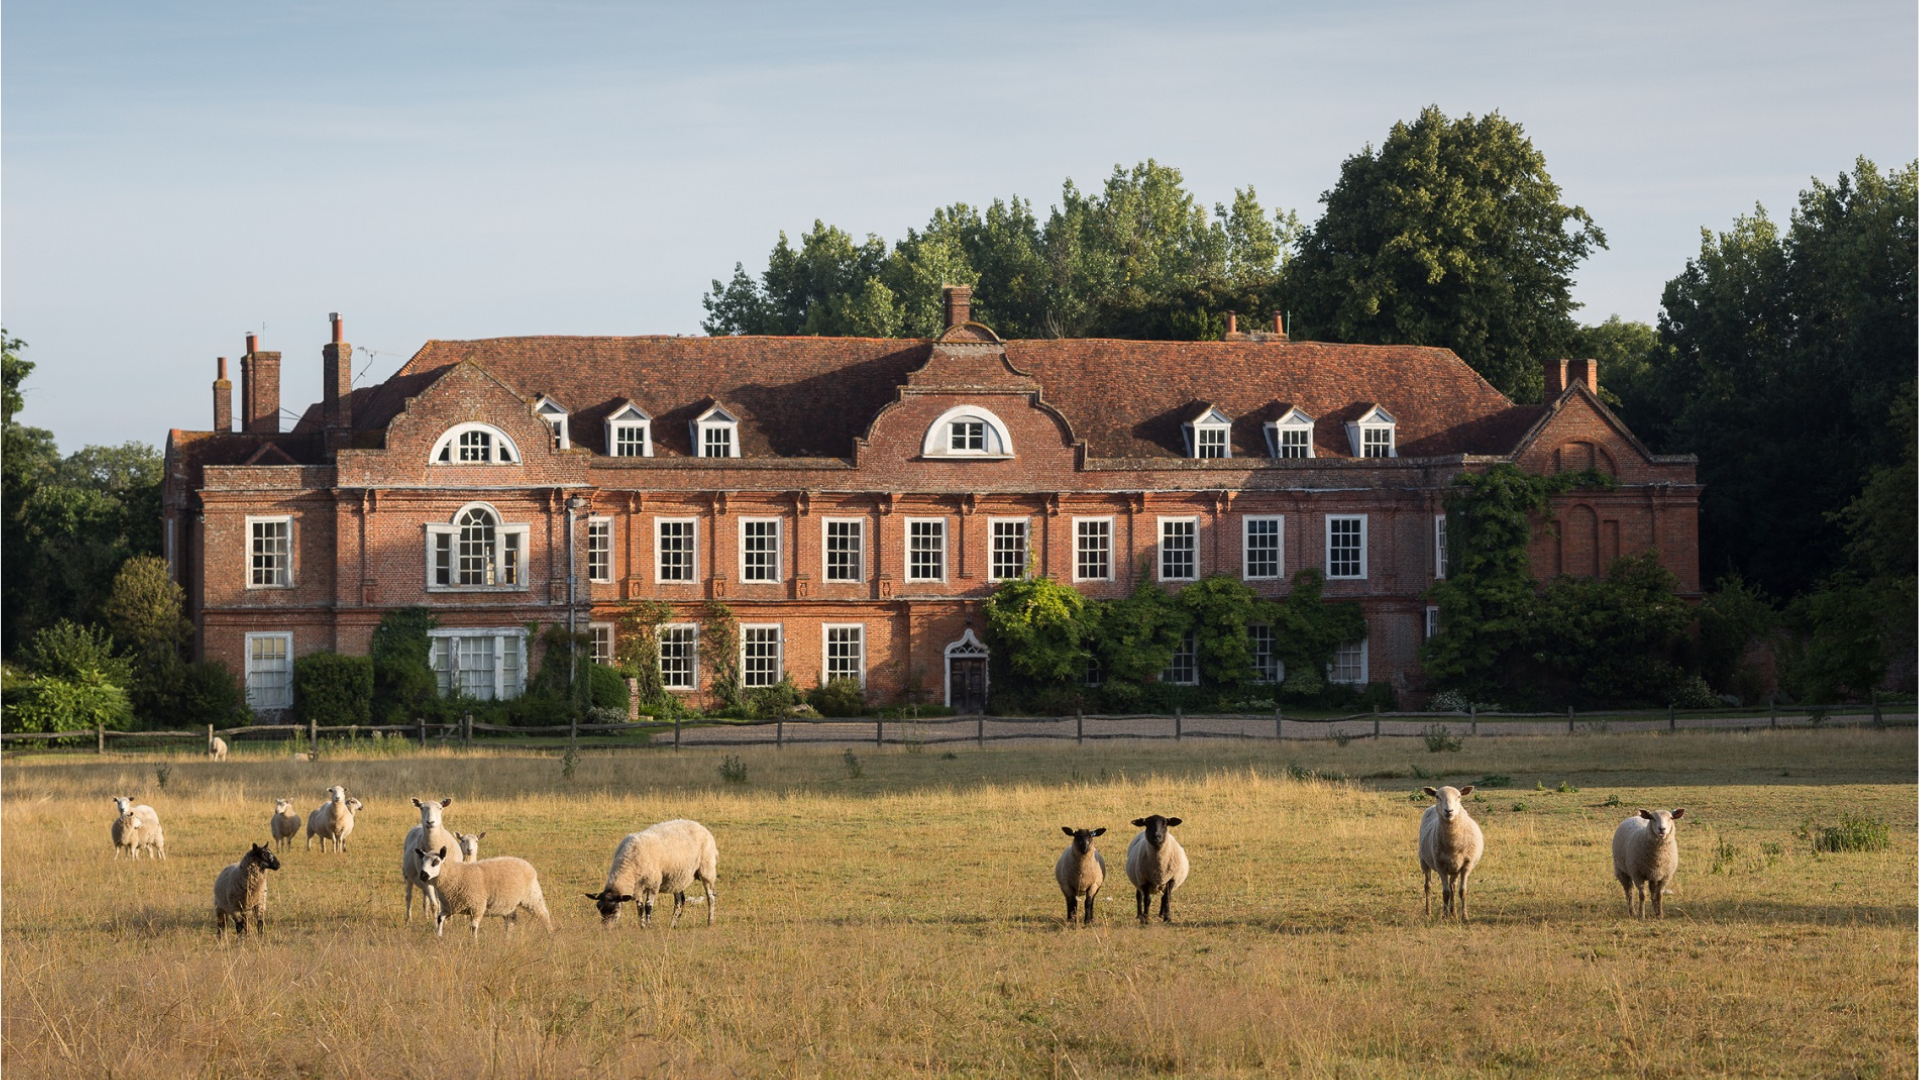
If you’re a fan of the hit BBC TV comedy ‘Ghosts’, it will.
Because West Horsley Place is Button House!
And do you know what? It looks EXACTLY like it does on the telly – outside and in.
So not only will you get to take part in the Big Day Out, you can sneak a few selfies in the Great Hall, the library, that long red room upstairs, the grand staircase, the garden, even the corridor that leads to the plague pit.
What’s more, we’ll took the traditional group photo in front of house.
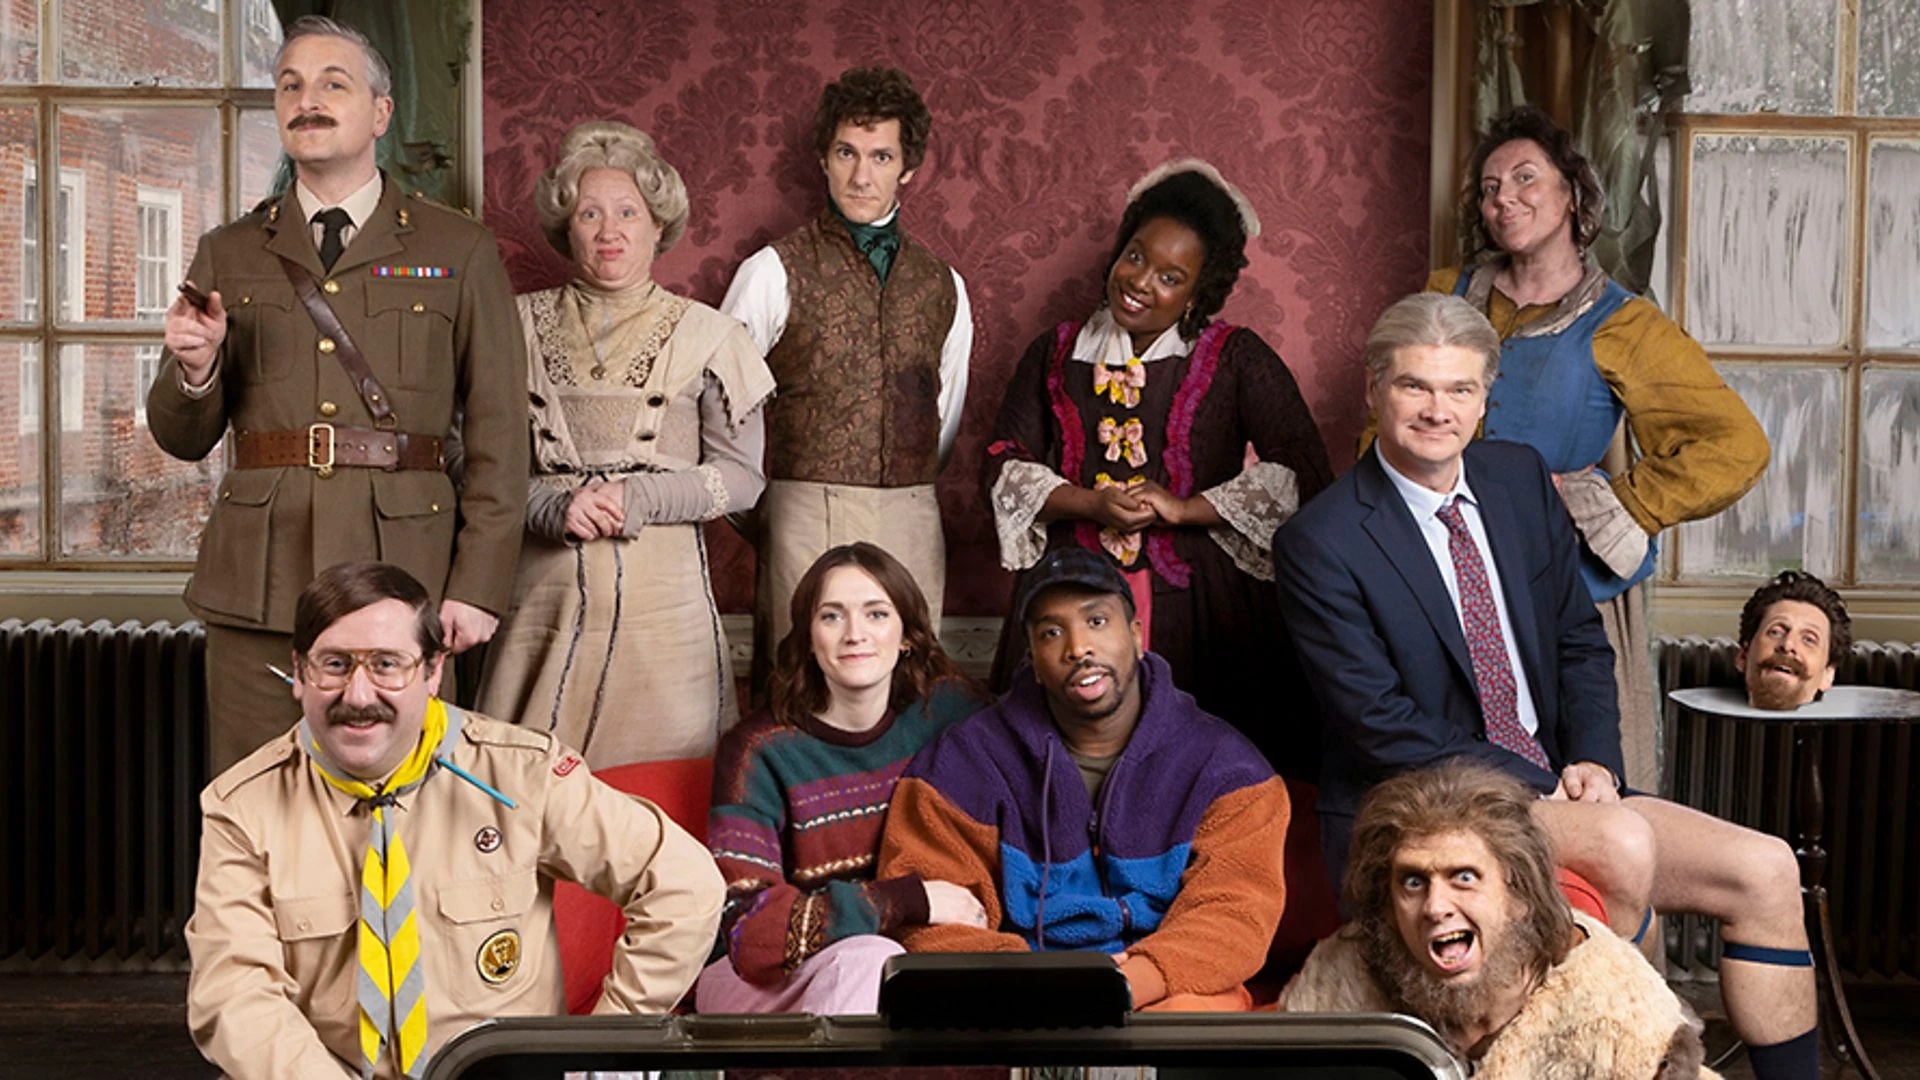
Roll the credits!
There are so many people to thank for making the Big Day Out Whodunnit possible – the cast of suspects, the Paraplannershire Police CID, our expert witnesses, our family of supporters and those meddling paraplanners!
Rather than list everyone individually, we created movie-style end credits (somewhat inspired by the Glass Onion series). If you took part, see if you can spot yourself. (Tap the replay icon in the bottom left of the picture to watch from the start.)
Temporary pension income guarantees are nothing new to retirement income planning. But how much do you actually know about how they work?
During this Online Assembly, Richard Allum and M&G’s Mark Devlin take a practical look at temporary pension income guarantees, and what they mean for cases that you may work on.
During this Assembly, Mark explained:
- what temporary guarantees are and how they work
- the options available to clients
- what happens to death benefits
- why you might consider using them in a client’s retirement plan
Plus they added a couple of real-world case studies into the mix to bring it all to life.
What can you expect to take away?
A clearer, more practical understanding of temporary pension income guarantees, and a sense of when and why they might be worth putting in front of a client.
Ready to top up your knowledge? Catch up now.
The near-Dickensian language of a Will doesn’t half make the clarity of its contents harder to grasp, doesn’t it?
And then there’s LPAs, which come with limits that catch you out. Things like what an attorney can and can’t gift, whether they can set up a trust, what happens if the attorney themselves loses capacity.
So if you’re prone to befuddlement – and, let’s be honest, who isn’t? – then tune into this conversation with Shaun Moore, Technical Specialist at Quilter.
Because Shaun joined us for a lunch-hour conversation that’s all about deciphering what wills and LPAs actually say.
But this isn’t about which form to fill in or which portal to log into. It’s a planning conversation about why these documents matter, what they can and can’t do, and what paraplanners need to look out for.
And with pensions becoming vulnerable to IHT, and plenty of plans now out of date, this is the ideal time to revisit both documents.
So during this Assembly we covered
- why pensions coming into the estate means old wills need a second look
- Residence Nil Rate Band (RNRB) pitfalls and old discretionary trusts left over from before the transferable nil rate band
- deeds of variation, and what your options are when a will hasn’t been drafted well
- investment powers in will trusts, including bonds for life tenants, STEP provisions and when the Trustee Act 2000 defaults apply
- the limits on what an attorney can do, including gifting and setting up trusts
- LPAs and discretionary fund management, and the Office of the Public Guardian’s reversed guidance on discretionary fund management (now allowed unless the document says otherwise)
- what happens when an attorney themselves loses capacity, and whether a will can be changed or revoked
What can you expect to take away?
Watch or listen and you’ll gain a clearer idea of the role of wills and LPAs so you can spot the planning opportunities.
Even very experienced paraplanners can trip over obstacles lurking in the shadows of IHT.
So we invited Aegon’s tax and trusts manager, Elaine Cruickshank, to join host, Richard Allum, for an online Assembly to help you dodge the IHT perils.
Over the course of one lunch-hour, Elaine:
- untangles the transferable nil rate band and residence nil rate band, including the detail that trips people up around second marriages and downsizing provisions
- gets into the finer points of gifting exemptions, PETs and CLTs, beyond the seven-year headline
- explains how the inclusion of pensions in estates affects the taper threshold, and what that means for clients close to the £2 million mark
- works through charitable giving and the 36% rate, including the added complications once pension funds are in the mix
- brings it all together with planning opportunities you can take straight back to your desk
What can you expect to take away?
Watch or listen now and you’ll have a sharper grasp of the IHT detail that’s easy to get wrong. Plus the confidence to spot these issues in your own client cases.
Watch or listen now
Missed it? Then follow the links below to download Elaine’s slides, watch the replay or catch up with the podcast now.
The outstanding questions
There were so many questions on this Assembly that we ran out of time, so Elaine has provided us with the answers to the outstanding questions, as well as provide a clarification on the final question of the Assembly.
Can the small gifts exemption and the annual £3,000 exemption be given to the same recipient?
If a gift in excess of the £250 small gifts exemption is made, then as this gift is more than the small gifts exemption, the full gift would be allocated against the annual exemption (assuming that this was available).
Why is it called Inheritance Tax? Shouldn’t it be called Estate Tax, as it is (normally) the estate that pays?
“Inheritance Tax” is a better reflection of what the tax is intended to cover — rather than simply being a tax on an estate at death, there could also be IHT applying to lifetime transfers.
Is it best to space significant gifts at least 7 years apart then?
Each gift has its own 7-year clock, but whenever a gift is being made you have to consider the cumulative impact of any gifts made in the previous 7 years. If the donor dies within 7 years of a gift, earlier gifts use up the nil-rate band first before later gifts are considered. Making very large gifts close together can therefore increase the IHT exposure of later gifts, if death occurs within 7 years. Taper relief may reduce the IHT on gifts made more than 3 years before death, but it does not reduce the value of the gift itself for nil-rate band purposes.
Does tax-free income from a beneficiary’s pension (where the spouse dies under age 75), either through an annuity or under FAD, count towards regular income when considering gifting out of surplus income?
This is a grey area and will probably require a tax case to provide clarification. As this money is completely exempt from income tax, HMRC could view the regular withdrawals of this nature as capital rather than income.
Is there a length of time for the ‘main residence’ qualification to be lost?
For the Residence Nil Rate Band, there is no specific minimum or maximum period between the property ceasing to be the deceased’s main residence and their death. The key point is that the property must have been a qualifying residential interest, meaning a property that the deceased occupied as a residence at some point during their ownership. For the downsizing addition, they have to downsize or dispose of the property on or after 8 July 2015, but there is no stipulated timeframe between the date of downsizing/disposal and death.
What if they still own the property but have also moved into a care home?
A property can qualify even if the individual was living in a care home at death, provided the property had been their main residence at some point and they leave the property to their direct descendants. The amount of residence nil rate band available will generally be the lower of the available RNRB and the value of the qualifying residential interest passing to direct descendants, and it may also be reduced by the taper reduction if the estate exceeds £2 million.
If they own a house worth less than the RNRB, should they upsize to make the most of it?
If they upsize and buy a bigger house, the value of the estate would generally remain unchanged — they now have a larger property and less cash. However, if they live in the bigger property as their main residence and leave this to their direct descendants in their will, then they could in theory qualify for the full residence nil rate band if the value of the house was equal to or higher than the residence nil rate band and the £2,000,000 tapering threshold was not breached. However, tax mitigation isn’t the only factor to consider here — there would be the costs of moving house, larger council tax and utility bills etc, which could be more significant than any IHT saving achieved.
Can RNRB apply to an IIP trust, where some people have moved their home into a solicitor’s trust and continued to live in it?
It sounds as though this type of arrangement would potentially be a gift with reservation of benefit, with the value of the property remaining in their IHT estates. Whether or not the RNRB would apply in this scenario would depend on the provisions of the trust. Are the direct descendants the beneficiaries of the trust, and do the trust provisions meet the conditions of ‘directly inheriting’ the property?
We all have pension questions we’ve never quite got round to asking. Maybe the moment wasn’t right. Maybe the right expertise wasn’t around. Maybe you just didn’t want to be the one to ask.
That’s why in this Assembly, we staged a pension intervention. Because host Richard Allum posed the most pressing pension-related questions to someone who just loves answering them: Quilter’s retirement and pension technical specialist, Adam Cole.
Over one lunch hour, we worked our way through pension topics that either crop up regularly in client cases or maybe just leave you scratching your head from time to time. Things like:
- Transitional tax-free cash, lump sum allowances and lump sum death benefit allowances
- Taking tax-free cash after 75 and the implications
- Taking protected tax-free cash and moving into drawdown
- How defined benefit pensions work
- Guaranteed annuity rates, guaranteed cash sums and other features of older-style contracts
What can you expect to take away?
Watch or listen now to brush up on your pension knowledge. And don’t forget to follow the link below to download your certificate for CPD.
The rules are changing and from April 2027 and unspent pension pots will fall within the scope of inheritance tax. Draft legislation is now published, and there’s plenty for paraplanners to get to grips with.
This Assembly looks at how we got here, and where we need to go with less than nine months to go. We looked at what the May 2026 HMRC technical note and draft legislation actually confirmed, what it means in practice, and, what it means for the planning advice paraplanners are helping to shape right now.
On 1 July 2026, host Richard Allum was joined by guest Mark Devlin, Senior Technical Manager at M&G, to practically address some of the trickier questions the changes raise.
Together, they covered:
- The background: how we got here, and what the consultation process did and didn’t address
- Discretionary vs directed schemes: a refresher on the distinction and why it matters for IHT treatment
- How the new process will work in practice, including the role of personal representatives
- Planning implications: is it still worth funding a pension, and at what level?
- Balancing pension use for retirement income against IHT exposure, and keeping an eye on taxable funds for beneficiaries
- A common income tax misconception, and why some recent press coverage has muddied the water
What can you expect to take away?
At the end of this Assembly, you’ll have a better understanding of the confirmed changes, a better grasp of the planning considerations that flow from them, and some practical frameworks to bring to your paraplanning work, whether you’re reviewing existing pension strategies or helping to shape new ones.